Donald Trump remains the settlor and sole beneficiary of his revocable trust. Donald Trump Jr. is its sole trustee, with voting and investment authority over its securities. Delegating investment decisions does not remove Trump’s economic interest: shares may generate dividends or gains, while debt produces contractual interest and repayment claims. [1,2]
Donald Trump Jr.’s trustee authority and Eric Trump’s operating role are distinct from their father’s beneficial ownership. Business revenue is not automatically personal profit; distributions, expenses, taxes and each entity’s ownership determine the amount reaching him. [1,2,27]
The climate-policy record also concerns public access to information. Taxpayer-funded climate research and tools were removed, rewritten or left without updates in documented cases, making information relevant to public understanding, health and safety harder to use. The report connects those changes with the energy-policy record and Trump’s disclosed oil and gas interests, while separating potential benefits from measured personal gains. [1,45,46,47]
The 2025 filing records $5,378,027–$23,273,000 across four companies with identified Greenland commercial connections or reported supply discussions. This is the combined value range of their disclosed securities, not money invested directly in Greenland or a forecast of takeover profits. [1,27]
Connection | Disclosed holdings | Evidence |
|---|---|---|
Halliburton | $18,004–$97,000 | Announced Greenland services agreement. [75] |
Lockheed Martin, RTX and Boeing | $5,360,023–$23,176,000 | Mineral supply discussions or planned talks. [79] |
Combined identified exposure | $5,378,027–$23,273,000 | Four company totals; no duplicate issuer entries. [1,27] |
Greenland restricted new oil licensing for environmental reasons; Trump’s energy policy promotes expanded development. If US control included resource‑policy authority, his administration could pursue wider drilling access, potentially benefiting companies in his portfolio. See Public Climate Policy and Trump’s Investment Portfolio and the Greenland sections for the policy record and dated acquisition pressure. [6,96,99]
At least seven documented occasions of Trump’s own military‑option statements, acquisition pressure or tariff threats are listed under Greenland: repeated threats and pressure, with dates and sources. [84,85,86,87,88,89,90]
On 6 January 2026 the White House described military force as an acquisition option. On 21 January Trump said he would not use force. At the NATO summit on 7 July 2026, he said Greenland “should be controlled by the United States.” [73,74,102]
The documented chain is Trump’s Halliburton securities, Halliburton’s commercial relationship with March GL, and the Greenland exploration project. That is a meaningful indirect financial connection. It supports a potential‑conflict flag without requiring proof that Trump owns the project. [1,4,5] Halliburton supplies expertise and services that can enable exploration. It is one supplier in the documented chain; the agreements do not establish that it is indispensable or the only available supplier. The wider portfolio spans producers, pipelines and oilfield services.
The 11 April 2025 agreement covers consulting. It expressly excludes well services and project management unless separately contracted. Work orders determine compensation; the agreement alone does not prove completed drilling, the amount paid, Halliburton’s profit, or a payment to Trump. [4]
A broader agreement announced on 27 April 2026 includes well and drilling services. The later announcement extends the documented relationship beyond the original consulting scope; it does not disclose a personal payment to Trump. [75]
On 11 August 2026, Greenland Energy said the permitting review would take longer and targeted winter 2027. This is a company planning target, not a granted permit, completed drilling or production revenue. The delay is material when evaluating any proposed route from policy to supplier earnings. [28]
The 4 April purchase of $50,001–$100,000 precedes the agreement by seven days. There were earlier purchases and sales and later sales and purchases. The sequence is documented; advance knowledge, coordination and a policy‑for‑profit arrangement are not established. [1,4]
Nine purchases total $86,009–$290,000; four sales total $81,004–$215,000. These are gross transaction bands, not ending holdings or trading profit. Six holdings rows total $18,004–$97,000 when two below‑threshold rows are included as $0–$1,000 each. [1,27] The appendix lists each account, filing page and row; purchases and sales across different accounts are not treated as one matched trade.
One holdings row reports a $201–$1,000 dividend band. This is evidence of disclosed investment income, not proof that Greenland work funded that dividend. Direct Trump ownership of the Greenland project and any project‑specific personal profit remain unestablished. [1]
Trump’s 2025 disclosure identifies $11.98 million–$44.13 million in oil and gas holdings, $73.60 million–$337.05 million in the selected technology basket, and $8.25 million–$32.60 million in defense and aerospace. The table pairs those financial interests with specific public decisions examined below. Crypto businesses add substantial disclosed receipts, although total personal capital invested is not established. SEC records identify Trump as the sole beneficiary of his revocable trust. [1,2,27]
Field | Disclosed financial measure | Selected overlaps examined |
|---|---|---|
Oil and gas | 47 companies$11,978,142–$44,131,000 | 3 highlighted actions: production directive; Golden Pass export extension; power plant carbon‑rule repeal. [6,36,43] |
AI and technology | 10 companies$73,596,082–$337,045,000 | 2: UAE technology framework and Microsoft UAE chip export approvals. [10,12] |
Defense and aerospace | 13 companies$8,251,059–$32,597,000 | 1 award example: Boeing F47 development contract. [7] |
Crypto and Bitcoin | Personal capital invested: not established. DT Marks SC reports $196,875,000 in entity proceeds. [1] | 4: Bitcoin reserve; SEC meme‑coin position; Binance civil dismissal; GENIUS Act. [16,17,71,72] |
Oil, technology and defense totals sum 2025 disclosure ranges, including some debt. The counts cover the selected actions named above, not every possible policy overlap. Crypto proceeds are a receipt measure, not an investment balance.
Government actions are identified by their form: executive order, agency rule or decision, legislation or proposal, and public statement. A private agreement or securities trade is recorded separately. Timing can establish a sequence and a potential conflict; it does not alone establish a legal violation or personal profit.
The report follows ownership, investments, decisions and financial results, including climate effects, crypto investor outcomes and Kushner’s investment business. Exact gains attributable to individual policies remain unmeasured. Numbered references link to the underlying evidence.
Holding or business | Dated figure | Meaning |
|---|---|---|
Trump Media shares in trust | 114,750,000 shares; 41.5% in December 2025 filing | A dated equity interest; the percentage can change with new shares. [2] |
Mar a Lago Club LLC | 99.99% held by trust; $77,482,488 reported resort revenue for 2025 | Gross business revenue, not personal after‑tax profit. Schedule 1, line 180. [1] |
The 17 December 2024 transfer of Trump Media shares to the trust was disclosed as neither a purchase nor a sale. It belongs on an ownership timeline, not in a total of money spent buying stock. [1]
Trump’s financial interests extend to token businesses, a stablecoin venture and Trump Media’s Bitcoin activity. His sons also participate in American Bitcoin. The policy overlap includes the federal Bitcoin reserve, stablecoin legislation and the SEC’s approach to crypto enforcement. The family’s business receipts and each policy’s effect on them are separate measurements. [1,23,25,16,17,71,72]
Decision and date | Financial connection | Recorded effect / remaining amount |
|---|---|---|
Bitcoin reserve6 March 2025 | Trump Media’s later Bitcoin activity; family‑linked American Bitcoin. [23,25,71] | Order retains forfeited federal Bitcoin and directs budget‑neutral acquisition strategies. Supports federal recognition of Bitcoin; no gain or payment to the family is calculated. |
SEC meme‑coin statement27 February 2025 | The $TRUMP token venture. [1,72] | Staff viewed the described meme coins as outside securities registration. Nonbinding; no specific $TRUMP ruling. Other fraud laws remain applicable. |
Binance civil dismissal29 May 2025 | MGX had selected family‑linked USD1 for its $2 billion Binance investment on 1 May. [15,17] | Civil case dismissed on stated policy grounds. Settlement use expands USD1 activity; no government‑action‑for‑payment agreement established. |
GENIUS Act18 July 2025 | The USD1 stablecoin business and disclosed Stablecoin Holdco interest. [1,16] | Federal framework includes reserve and disclosure requirements. Potential commercial benefit from clearer rules; incremental family earnings attributable to the law are unmeasured. |
Schedule 1 reports $196,875,000 in DT Marks SC proceeds associated with capital contributions and Class C unit sales, alongside a 38.25% interest in Stablecoin Holdco. That is a reported entity receipt, not a calculation of profit caused by the GENIUS Act. [1]
Holding federal Bitcoin rather than selling it can reduce potential government selling pressure; official adoption can also affect demand. These are possible market channels, not a measured price effect. The reserve order does not direct purchases of the $TRUMP token or payments to a family company. [71]
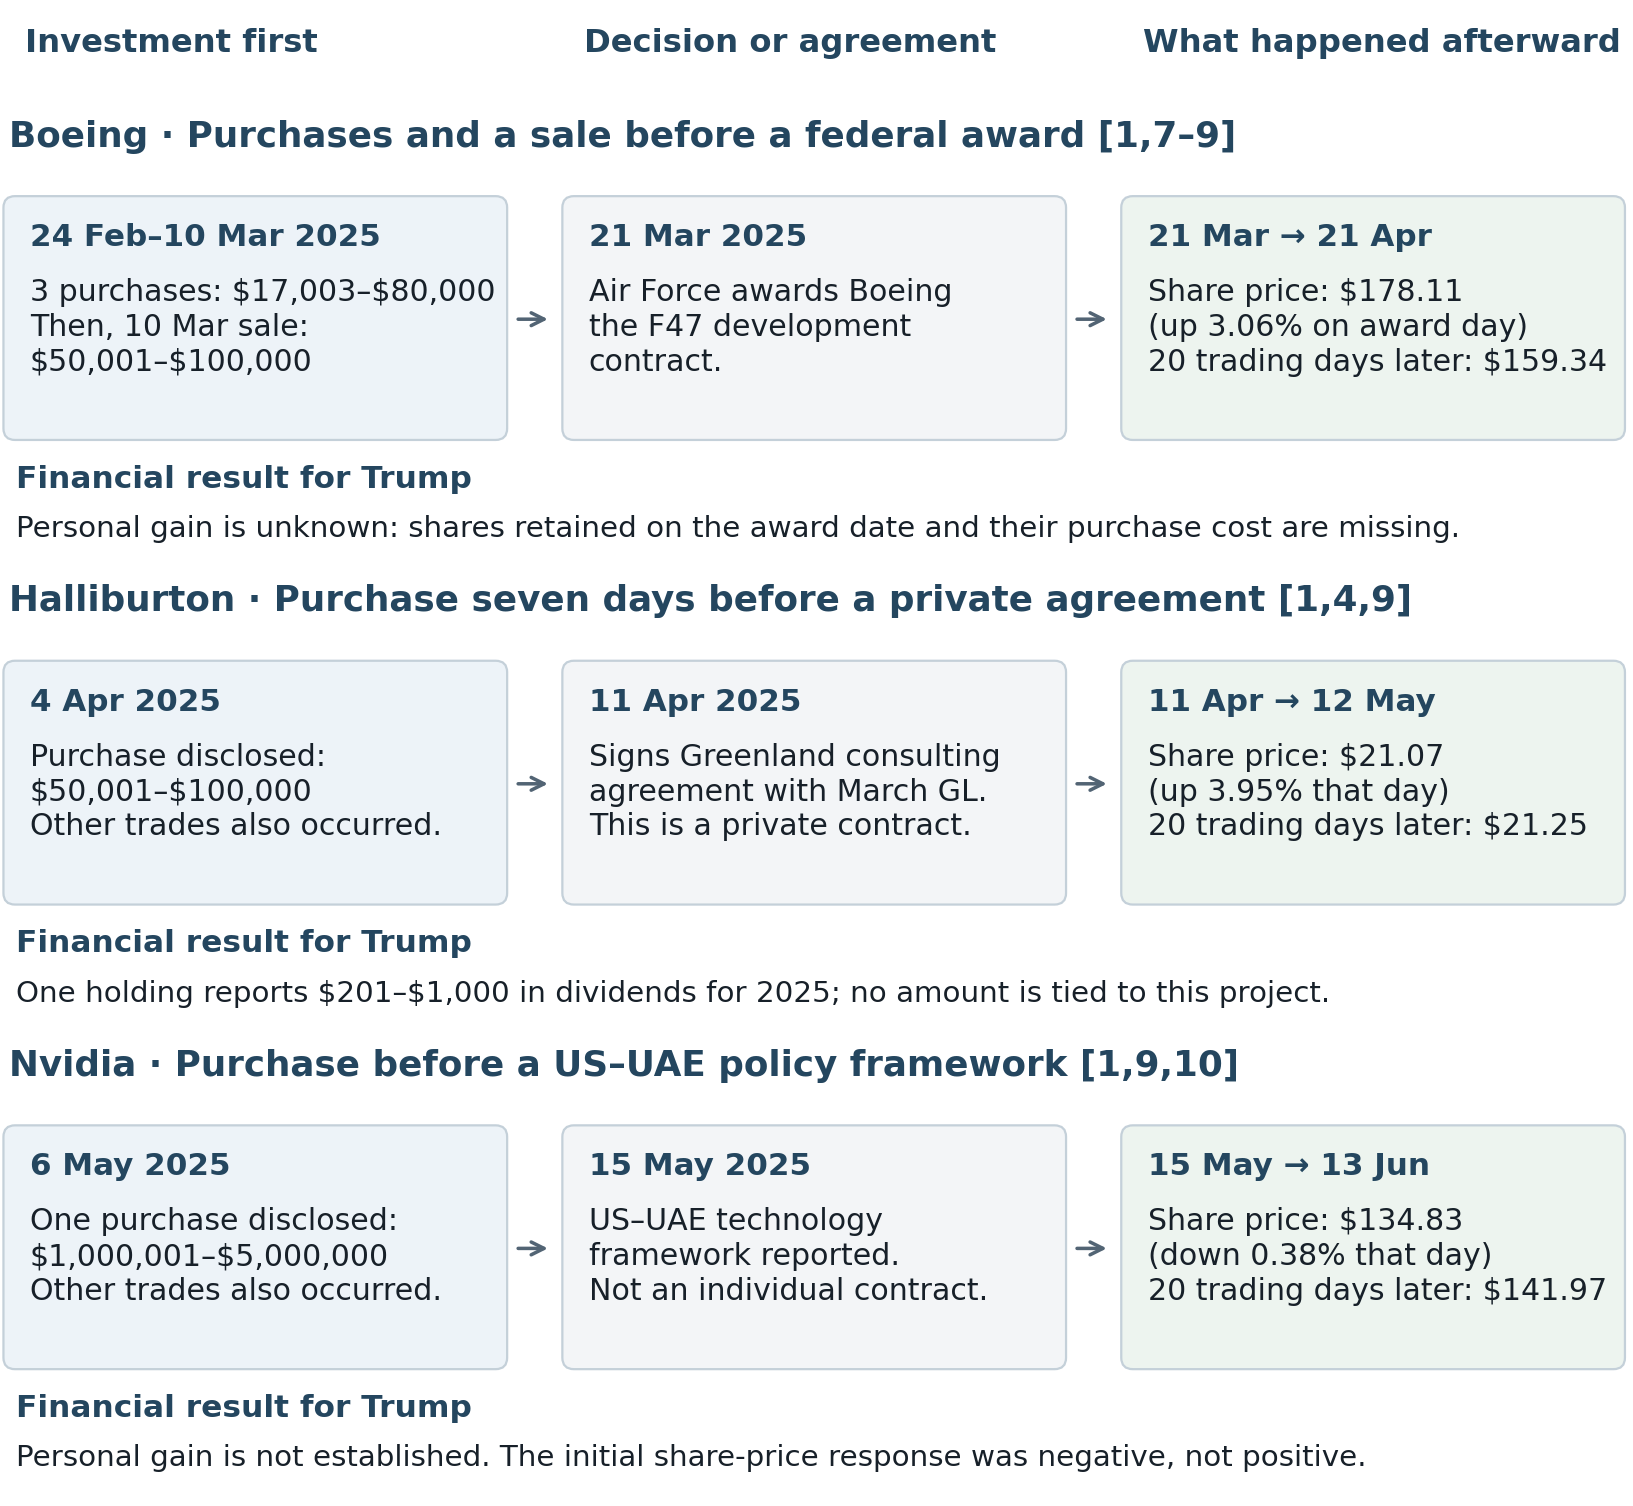
The records show purchases before important decisions, but the financial result is different in each case. Boeing’s shares rose on its award date; Nvidia’s fell on the framework date. A Halliburton dividend is disclosed, but no portion is traced to the Greenland project. [1,4,7,9,10]
Selected examples, not a complete trading history. Arrows show sequence, not proof that the decision caused the price change. Steps are equally spaced for readability; the detailed chart below uses a true calendar scale. Prices are per share in USD; percentage changes compare with the previous trading day.
Price trends and disclosed trades share the same 2025 date axis. Upward triangles mark purchases; downward triangles mark sales. Multiple transactions on the same date can overlap. Marker size does not represent transaction size. [1,9,27]
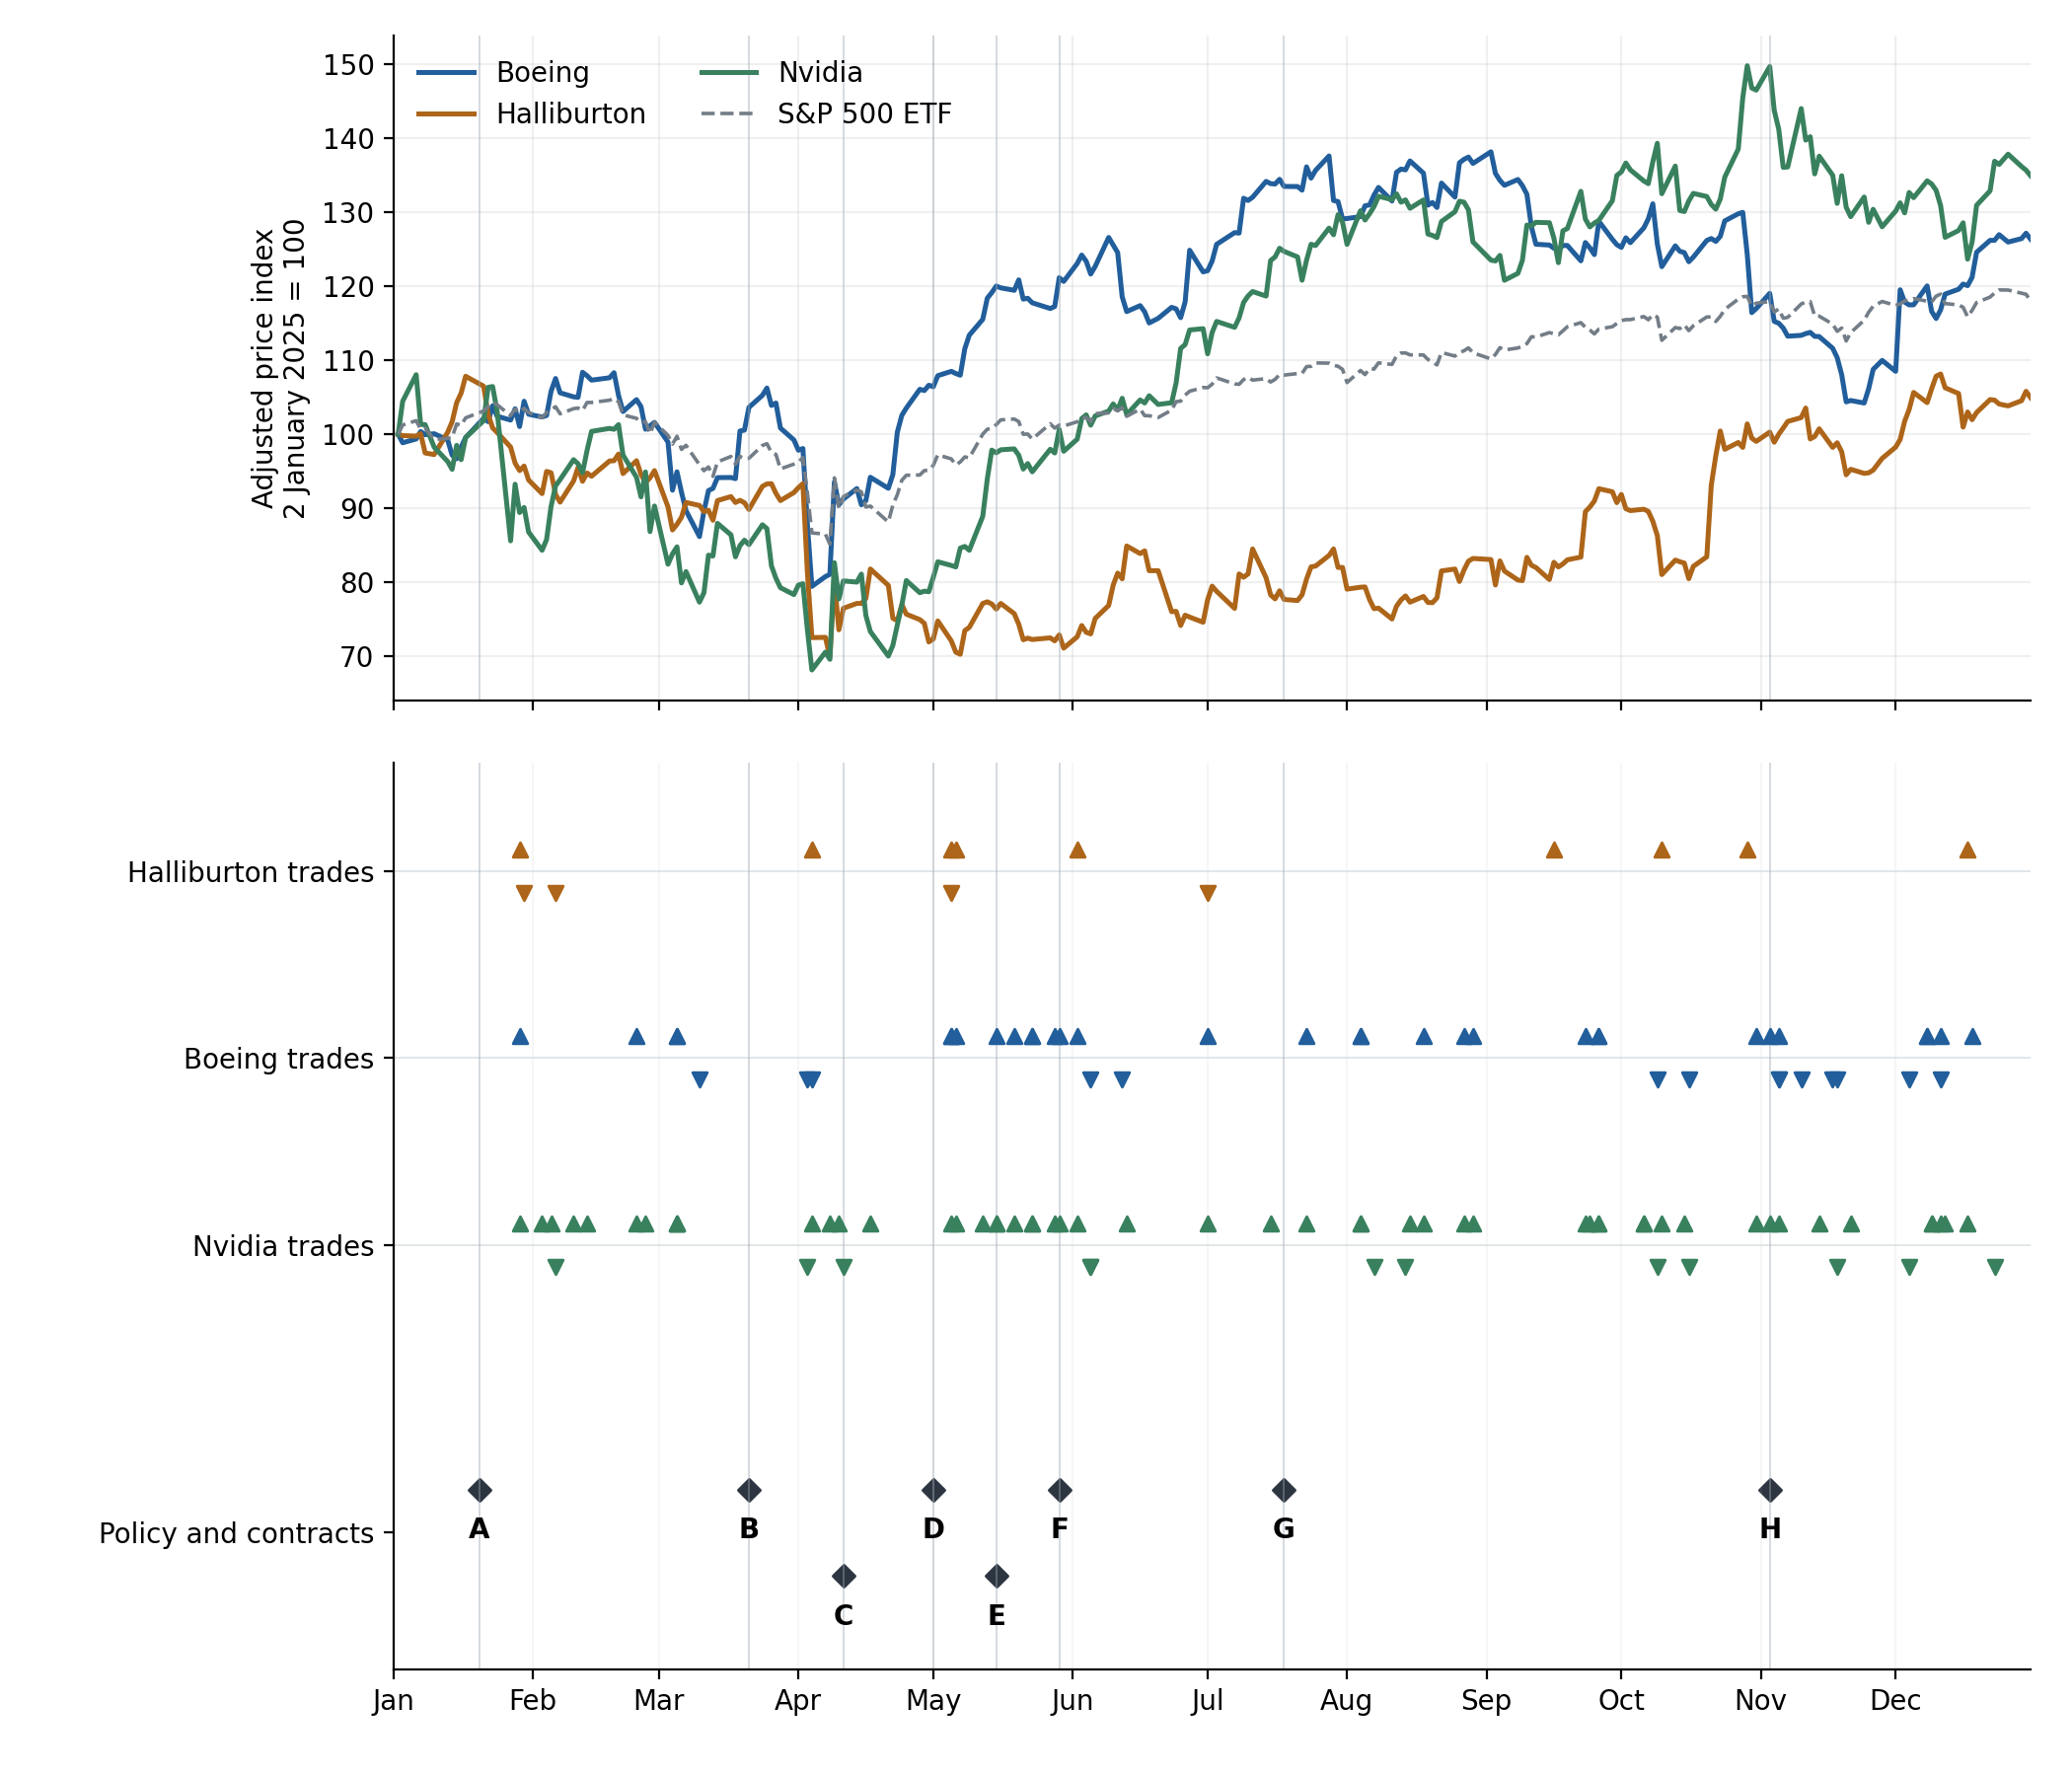
Key | Event | Evidence |
|---|---|---|
A | 20 Jan • Energy executive order | [6] |
B | 21 Mar • Boeing F47 award | [7,8] |
C | 11 Apr • Halliburton private consulting agreement | [4] |
D | 1 May • USD1 selected for MGX settlement | [15] |
E | 15 May • US and UAE technology framework | [10] |
F | 29 May • Binance civil case dismissed | [17] |
G | 18 Jul • GENIUS Act signed | [16] |
H | 3 Nov • Microsoft UAE export approval announcement | [12] |
The question is what changed after a decision and whether Trump received a financial benefit. Boeing’s initial price rise later reversed; Halliburton stayed slightly above its agreement‑day price; Nvidia’s May decline later reversed. None of those price paths alone measures Trump’s personal return. [1,9]
The table shows the closing price of one share before the event, on the event date, and 20 trading days later. The final column shows the broad market’s change on the event day. It does not show the value of the whole company or the return on its bonds. [9]
Event | Prior close | Event closeand return | 20 tradingdays later | Marketreturn |
|---|---|---|---|---|
Boeing F47 award2025‑03‑21 | 2025‑03‑20$172.83 | $178.11+3.06% | 2025‑04‑21$159.34 | +0.03% |
Halliburton private agreement2025‑04‑11 | 2025‑04‑10$20.27 | $21.07+3.95% | 2025‑05‑12$21.25 | +1.78% |
US and UAE framework2025‑05‑15 | 2025‑05‑14$135.34 | $134.83-0.38% | 2025‑06‑13$141.97 | +0.49% |
UAE export approval announcement2025‑11‑03 | 2025‑10‑31$202.49 | $206.88+2.17% | 2025‑12‑02$181.46 | +0.19% |
Prices are USD closing prices. Percentage returns use the adjusted‑close series consistently, including the S&P 500 ETF benchmark. The benchmark matters because broad market moves can dominate the response to any one event. Adjusted closes can incorporate dividends and subsequent adjustments. [9]
Boeing rose from $172.83 on 20 March to $178.11 on the award date, a 3.06% change. The contract is an economically relevant development. The holding records include purchases before the award, but also a sale before it. Exact shares retained on the award date and any realized gain are not established by the value bands. [1,7,9,27]
Halliburton rose from $20.27 to $21.07 across 10–11 April, while the broad market also rose. The consulting agreement’s execution date is not necessarily the date investors first learned of it. This comparison does not establish that the private agreement caused that price move. [4,9]
Nvidia fell slightly on 15 May despite the reported framework. A policy potentially favorable to a company need not produce an immediate positive stock return. Other information, expectations and market conditions affect the price. [9,10]
Company stock market value is share price multiplied by shares outstanding on that date. Enterprise value also accounts for debt and cash. Those inputs are incomplete here. Personal gain needs exact quantities, costs, sales, dividends and ownership share; applying a price change to a later holdings band cannot replace them.
Expected return also needs a time period, supported assumptions and a model of policy effects and other market forces. The disclosure bands cannot provide that forecast. An unmeasured benefit is unknown, not necessarily zero.
Trump’s identified 2025 oil and gas holdings total $11,978,142–$44,131,000 across 47 companies. These include producers, pipelines and oilfield services. They do not establish that Trump personally owns the drilling acreage of each company. Policy that improves a supplier’s commercial prospects can still create a financial incentive for its investors. [1,27]
Issuer | Sum of 2025 disclosed bands | Rows |
|---|---|---|
Exxon Mobil | $3,180,009–$12,450,000 | 9 |
Chevron | $2,595,010–$11,350,000 | 10 |
ConocoPhillips | $647,008–$1,430,000 | 8 |
Kinder Morgan | $1,169,008–$5,461,000 | 9 |
Williams | $418,007–$945,000 | 7 |
Halliburton | $18,004–$97,000 | 6 |
Six‑company subtotal: $8,027,046–$31,733,000. [1,27]
A broader Democratic Joint Economic Committee staff analysis reports $12,541,161–$45,557,000 in 2025 oil and gas exposure. Its coverage is different; the two totals are alternatives with different scope, not amounts to add together. This report does not adopt the staff’s estimated later appreciation as proven current wealth. [3]
Issuer | Disclosed band sum | Rows |
|---|---|---|
Occidental | $1,017,004–$5,083,000 | 7 |
Baker Hughes | $268,007–$695,000 | 7 |
Phillips 66 | $383,007–$896,000 | 8 |
Marathon Petroleum | $353,006–$745,000 | 6 |
Valero | $348,008–$795,000 | 8 |
SLB | $32,004–$130,000 | 4 |
The full identified oil and gas basket totals $11,978,142–$44,131,000 across 47 companies and 178 filing rows. The complete company list appears in the appendix. This is the best supported range for this defined basket, not an exact total of every direct and indirect investment. [1,27]
The 20 January 2025 energy order promotes domestic production and changes in permitting policy. Trump’s issuer holdings create a potential financial overlap with those policies. The economic effect is not uniform: lower oil prices can hurt producers even as more drilling supports service demand. Each company and policy needs its own analysis. [6]
Security type matters. The Occidental entries include debt; some other issuer totals also combine securities. A bondholder’s benefit follows interest payments and credit risk, not the same payoff as a shareholder. Fund holdings can create additional indirect exposure, which is not included in the named‑company subtotals. [1,27]
Trump’s identified oil and gas holdings total $11,978,142–$44,131,000 across 47 companies in the 2025 disclosure. The policy record has two connected dimensions: how policy changes a business’s prospects, and how it changes the climate. The Golden Pass extension is a specific benefit to an Exxon‑linked project. EPA’s power plant analysis separately projects more carbon dioxide after its repeal. Trump’s disclosed investments make the financial connection relevant, but do not measure his personal gain from either action. [1,36,43,44]
Greenland presents a related policy contrast: its government stopped new oil licensing partly to protect the environment, while Trump promotes expanded energy development and has sought control of the territory. If US control included authority over resource policy, his administration could pursue wider drilling access, potentially benefiting companies in his disclosed portfolio. The Greenland sections set out the restrictions, commercial connections and dated threats. No resulting personal gain or financial motive is established. [1,6,75,96,99]
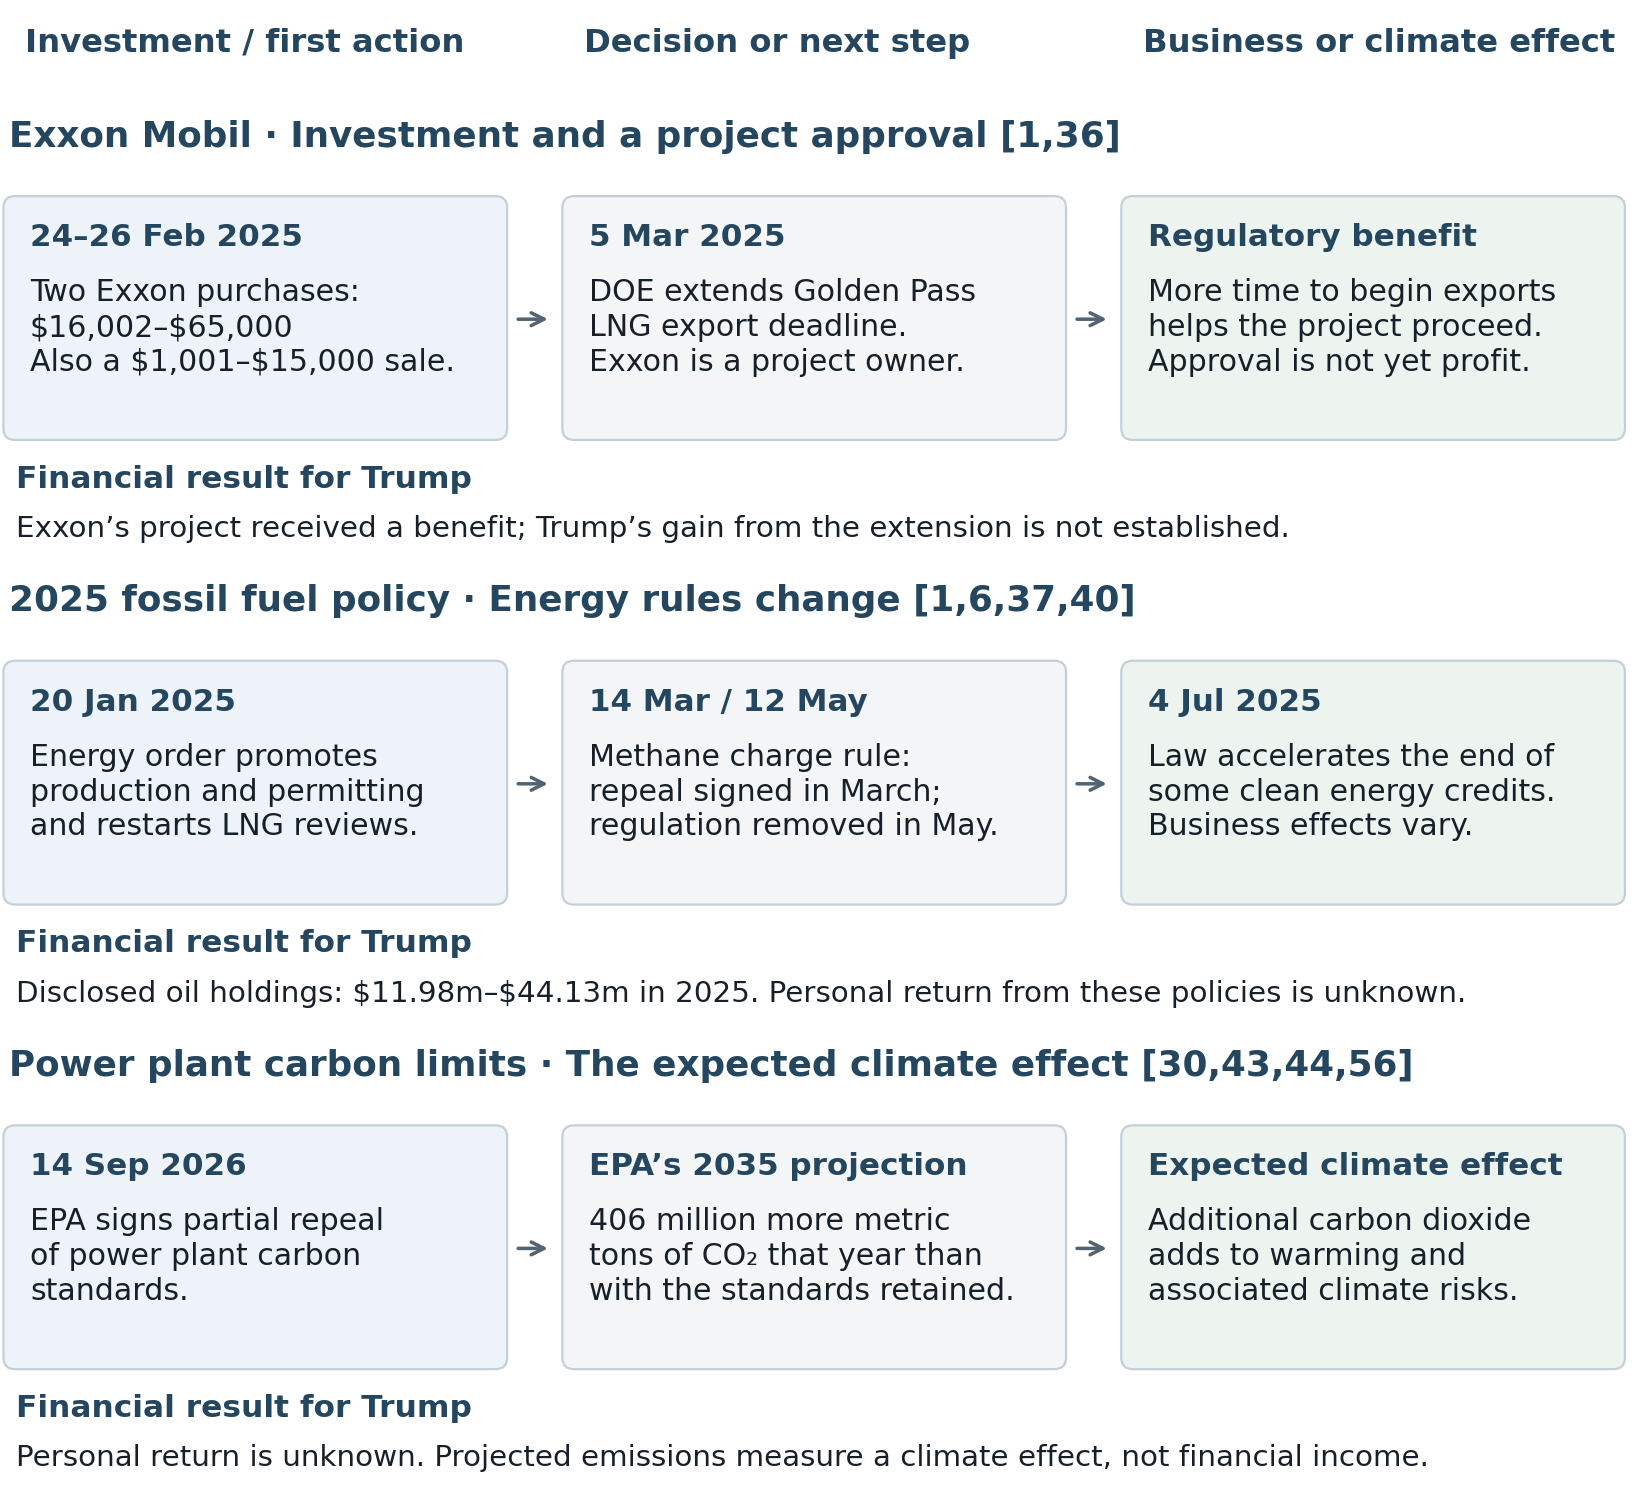
These are selected sequences, not a scale drawing of elapsed time. The 2025 holdings range is not an exact balance on each policy date. EPA’s 2035 emissions figure is a projection relative to keeping the standards, not an observed increase.
Trump’s identified 2025 holdings in 47 oil producers, pipeline companies and drilling suppliers total $11,978,142–$44,131,000. His administration has also expanded support for fossil fuels and removed important climate protections. These records establish that his public decisions affect businesses in which he has a financial interest. They do not, by themselves, tell us how much a particular decision added to his personal income. [1,6,36,42,43]
A permit can help a company complete a project. Lower compliance costs can improve a company’s finances. Policies that slow the shift away from fossil fuels can support demand for its products. Investors can share in the results through dividends, interest or changes in investment value. Each step is a different fact to check; a company receiving a benefit does not show the amount its investor received.
Documented interest | Government action | Business effect to examine | Financial result for Trump |
|---|---|---|---|
Exxon Mobil$3,180,009–$12,450,000 | DOE extended the Golden Pass LNG export deadline on 5 March 2025. [36] | Exxon is a project owner. More time protects the project’s ability to proceed. | No personal gain from the extension is established. Company earnings and shareholder returns are later steps. |
Chevron and ConocoPhillips$3,242,018–$12,780,000 combined | Production and permitting support; removal of methane charge implementing rule. [6,37] | Possible operating cost and development benefits. Lower oil prices can offset them. | Policy‑related gain is not calculable from the value bands; costs and quantities are missing. |
Kinder Morgan and Williams$1,587,015–$6,406,000 combined | Policies supporting oil and gas production and LNG exports. [6,36] | More gas transport can support pipelines, depending on contracts and volumes. | Potential investment benefit; no amount is traced to these policies. |
Halliburton$18,004–$97,000 | Production policy and the separate Greenland consulting contract. [4,6] | More drilling can support services demand. Private Greenland work has permit conditions. | One holding reports $201–$1,000 dividends in 2025. No amount is tied to Greenland work. [1] |
Amounts are sums of 2025 disclosure ranges. The table describes possible business effects, not measured gains to Trump. The year‑end record does not establish the number of shares held on every policy date. [1,27]
The White House has said independent third‑party managers execute portfolio trades and follow recognized indexes. That response matters when asking who chose a purchase. It does not remove the financial interest shown by the disclosure, and it does not establish how a particular official decision was made. [29]
This timeline places 244 identified transactions in six oil and gas companies on the same calendar as selected policy events. Both purchases and sales are included. It shows overlap in time; it does not establish advance knowledge or coordination. [1,27]
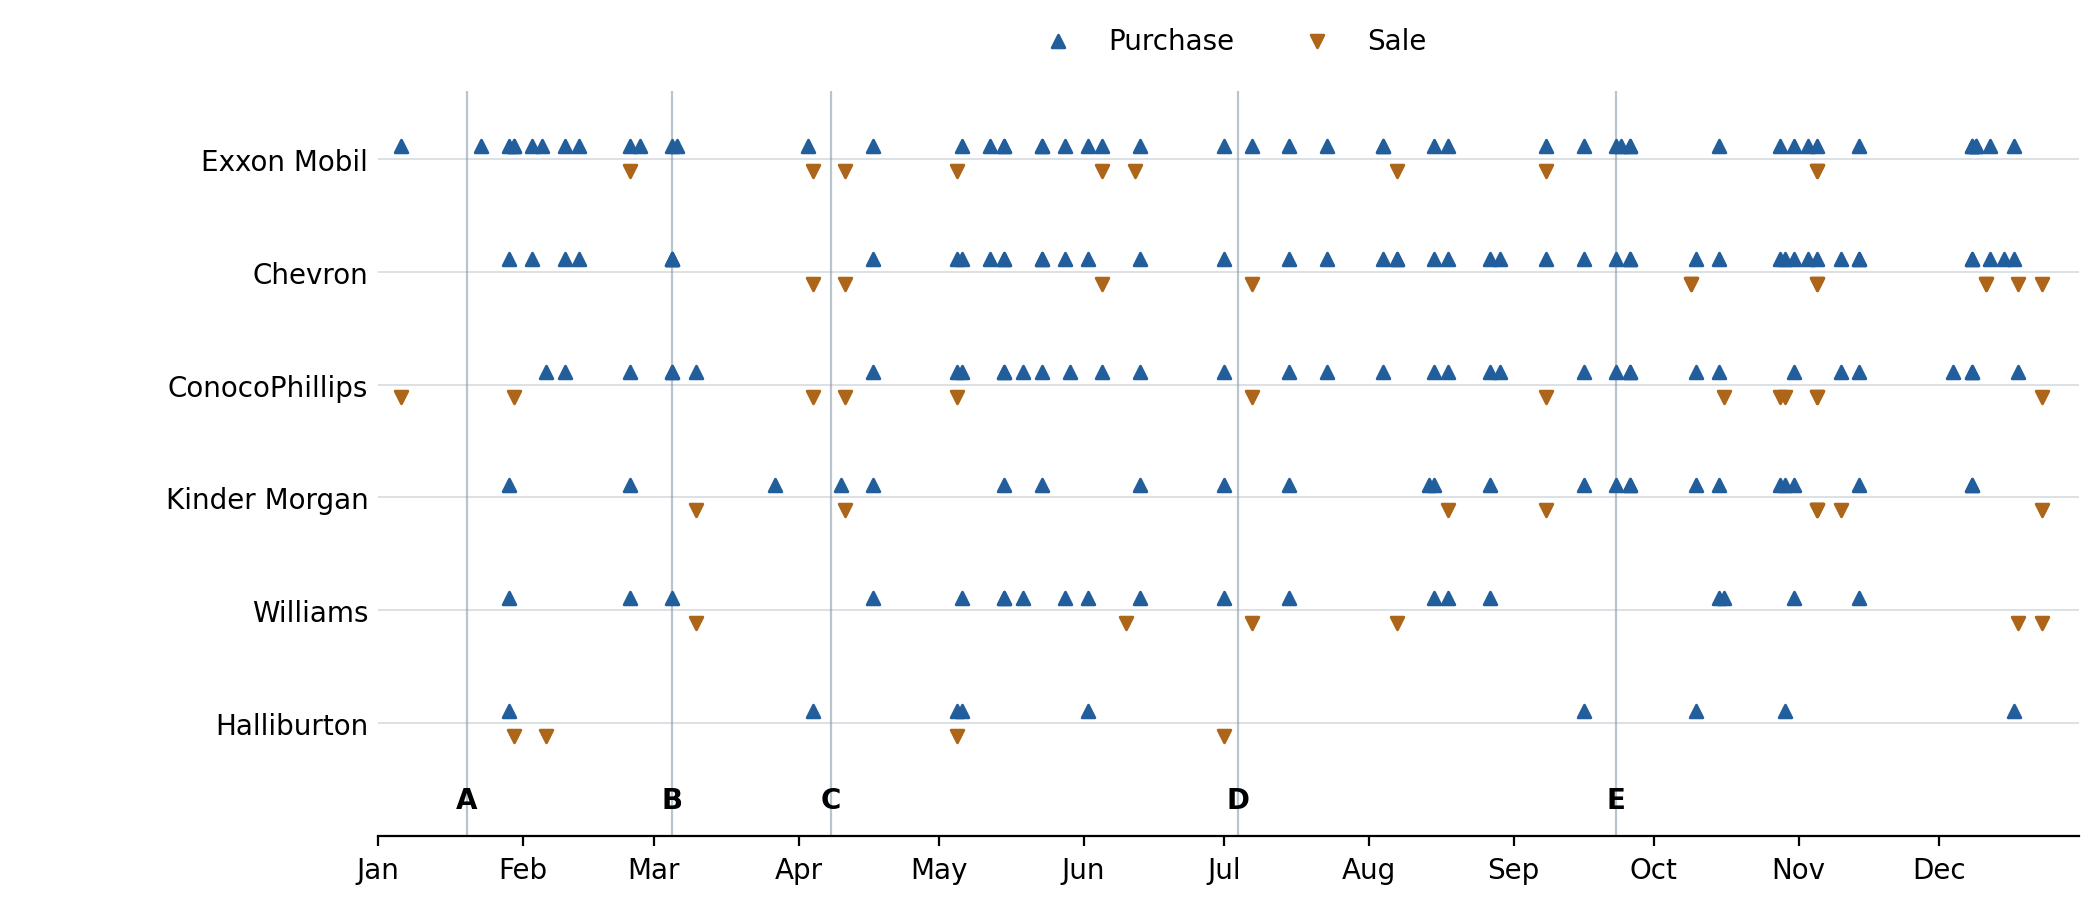
Key | Dated event |
|---|---|
A | 20 January 2025 • Energy, Paris and wind directives [6,33,34] |
B | 5 March 2025 • Golden Pass export deadline extended [36] |
C | 8 April 2025 • State climate challenge and coal directives [38,39] |
D | 4 July 2025 • Tax law changes clean energy credits [40] |
E | 23 September 2025 • Trump climate remarks at the UN [54] |
Date | Action and disclosed range | Account / page / row |
|---|---|---|
2025‑02‑24 | Purchase $15,001–$50,000 | 7 / 652 / 8271 |
2025‑02‑24 | Sale $1,001–$15,000 | 8 / 831 / 3536 |
2025‑02‑26 | Purchase $1,001–$15,000 | 8 / 780 / 1950 |
2025‑03‑05 | Purchase $1,001–$15,000 | 8 / 769 / 1600 |
2025‑03‑06 | Purchase $1,001–$15,000 | 8 / 789 / 2228 |
There were purchases and a sale before the extension, plus a purchase on the announcement date. The filing gives dates, not intraday times or trading instructions. It therefore cannot establish whether the same‑day trade preceded the announcement. [1,36]
The following register covers major documented actions relevant to the financial and climate questions. It is not a complete inventory of every federal rule, permit, lawsuit or website edit. The action’s stage matters: a directive, a proposal and a completed repeal have different effects.
Date and action | What changed | Status and relevance | Financial result for Trump |
|---|---|---|---|
20 JanEnergy order | Promotes production and permitting; restarts LNG reviews; withdraws the existing social cost of greenhouse gases framework. [6] | Signed directive. Can affect production costs and how agencies weigh climate damage. | Possible investment benefit; no personal return is measured. |
20 JanParis directive | Directs withdrawal notices and revokes the international climate finance plan. [33] | Signed directive. Reduces federal commitment to international climate cooperation; no company payment is established. | No direct payment or policy‑specific gain established. |
20 JanWind pause | Orders a pause in federal wind approvals and withdraws offshore areas from new wind leasing. [34] | The blanket agency permitting halt was rejected by a judge on 8 December 2025. [35] | No measured gain; court reversal affects the policy’s duration. |
5 MarGolden Pass LNG | Extends the deadline to begin exports from the Exxon and QatarEnergy project. [36] | Granted extension. A specific regulatory benefit to a business connected to a disclosed investment. | Exxon investment creates an indirect interest. Personal gain unknown. |
14 Mar and 12 MayMethane charge rule | Trump signs congressional disapproval; EPA removes the implementing regulation from federal rules. [37] | Completed rule repeal. Reduces this regulatory pressure on oil and gas operators. | Potential indirect benefit from costs avoided; amount unknown. |
8 AprState climate measures | Directs the attorney general to challenge specified state climate laws, penalties and lawsuits. [38] | Direction to take legal action. It does not automatically cancel those laws or claims. | No realized gain established from the directive alone. |
8 AprCoal expansion | Promotes coal leasing, exports and regulatory changes; calls for studying coal power for AI data centers. [39] | Signed directive. Coal benefits must be examined separately from oil and gas holdings. | No coal‑specific personal return calculated. |
4 JulEnergy tax credits | Accelerates the end of clean vehicle and specified home energy credits. Vehicle deadline: 30 September; home deadlines: 31 December 2025. [40] | Enacted law and IRS guidance. Removes some support for alternatives to fossil fuel use; not every clean energy credit ends. | Possible fossil fuel demand benefit; no personal amount established. |
Date | Action and stage | Effect to examine | Financial result for Trump |
|---|---|---|---|
7 Jan | Direction to withdraw from named international bodies, including the IPCC and UNFCCC. [41] | Reduces US participation and funding as implemented. Not every legal withdrawal is verified as complete. | No direct payment or policy‑specific gain established. |
12 Feb | EPA final rule rescinds the vehicle greenhouse gas endangerment finding and related emissions standards. [42] | Removes a central basis for vehicle climate regulation. Ordinary air pollutant controls are separate. | Potential fossil fuel demand benefit; no personal return measured. |
14 Sep | EPA signs a final partial repeal of the 2024 power plant carbon standards and issues a broader proposal. [43] | The partial repeal is a final action. The broader rescission remains a proposal. | No personal return established from the repeal or its emissions effects. |
EPA’s own analysis estimates higher annual power plant carbon dioxide emissions than under the standards being repealed. These are modeled future effects, not emissions already measured. The comparison is especially useful because it comes from the agency carrying out the repeal. [44]
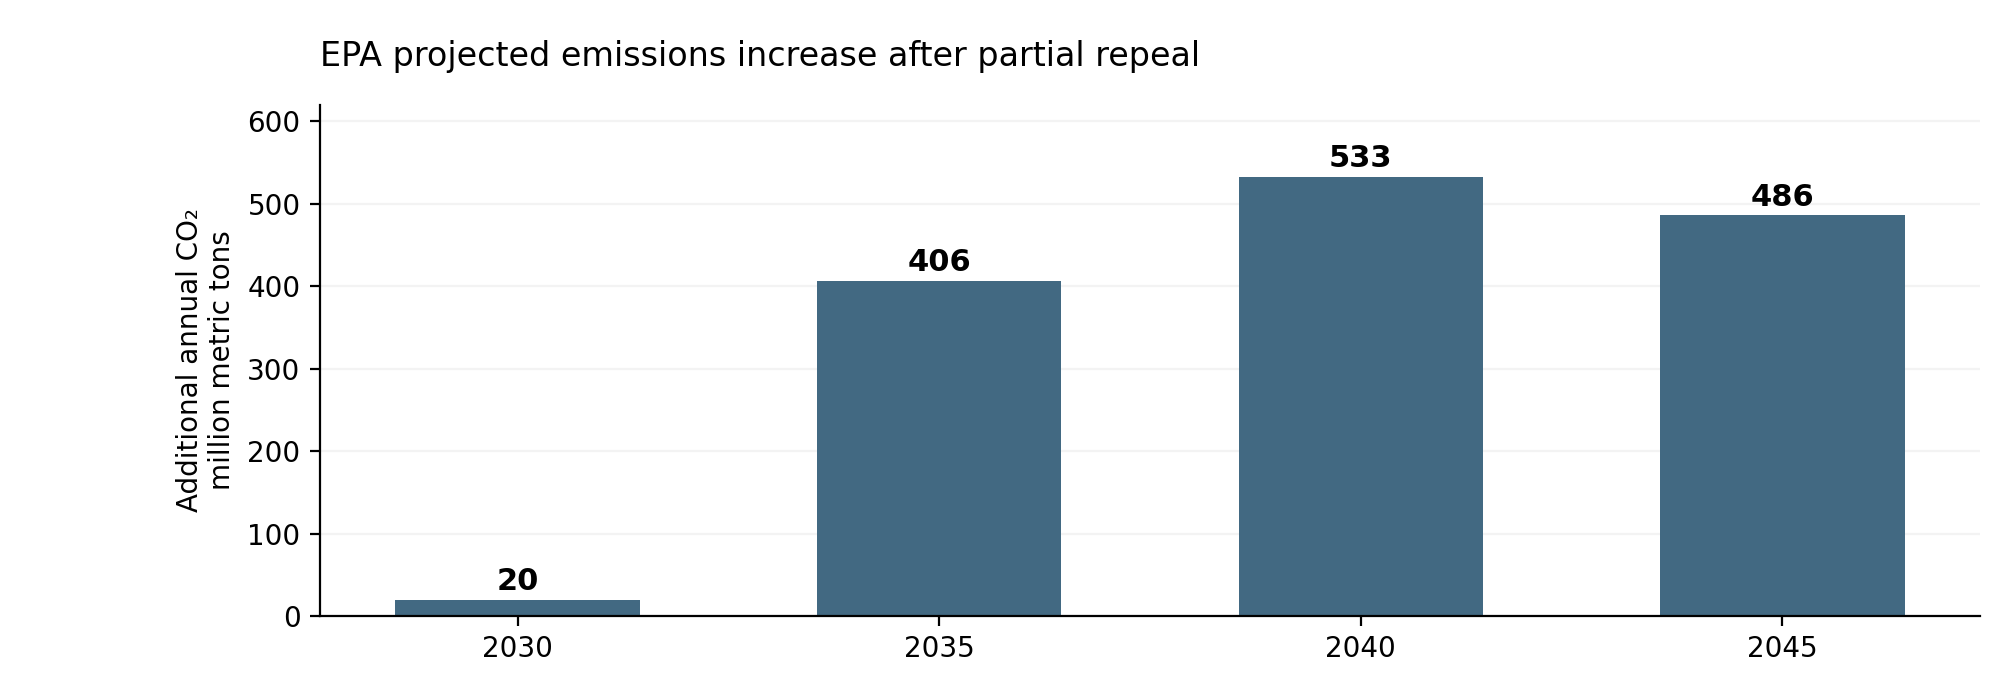
EPA Table 3‑3 reports increases of 20, 406, 533 and 486 million metric tons in 2030, 2035, 2040 and 2045 respectively. Its cost comparison does not assign a dollar value to the climate damage from those additional emissions. A stated compliance saving therefore does not measure the full social cost or benefit. [44]
The cause and effect is straightforward: removing the limits allows more carbon dioxide than keeping them, under EPA’s modeled conditions. That extra carbon dioxide traps heat and adds to global warming. Warming in turn increases risks from extreme heat, rising seas and changing rainfall. The effect is an increase compared with keeping the standards, even if total emissions fall for other reasons. The exact global temperature effect of this one repeal is not calculated here. [30,44,56]
Federal climate information was removed, rewritten or left without updates in documented cases. Taxpayers funded the research and tools. Reduced access makes it harder for people to understand climate risks and use information relevant to public health and safety. This does not establish that all underlying federal climate data was destroyed. [45,46,47]
Resource and date | Documented change | What remains or happened afterward |
|---|---|---|
USDA30 Jan 2025 | A directive ordered climate landing pages archived or unpublished. Farmers and advocates sued. [46] | USDA committed in May to restore pages. The case was dismissed on 25 February 2026. [46,47] |
EPA EJScreen and CEQ screening toolsEarly 2025 | EDGI documented removal of public screening tools combining environmental and community information. [45] | Archive comparisons show the specific pages and capture windows. These are access changes, not proof all underlying datasets were erased. |
NOAA Climate.govJune 2025 | The climate portal was redirected; its archive says maintenance ended on 25 June. [45,48] | Archived content remains. NOAA Climate Data Online remains available separately. [49] |
USGCRP and National Climate AssessmentsJuly 2025 | EDGI documented removal of the government portal and its assessment resources. [45] | Copies and archives preserve reports. Removing the portal reduces the public route to them. |
EPA climate causes pageDec 2025 | AP reported removal of the explanation connecting fossil fuel emissions to warming; natural drivers remained. [50] | This is a documented reported edit to particular content. NASA still explains human‑caused warming. [30] |
Whether a particular removal violated the law depends on the agency’s duties, the material and the procedure used. The USDA plaintiffs challenged the removals on those grounds. A restoration commitment and dismissal do not establish a ruling that every climate webpage change across government was unlawful. [46,47]
The website dates are observed changes, archive dates or reporting dates as identified above. They should not all be read as dates on which Trump personally instructed an agency employee.
In August 2025, AP reported an administration effort to end funding for OCO‑2 and OCO‑3, missions that measure atmospheric carbon dioxide and plant activity. That was a proposed termination, not evidence that the instruments had already stopped. [51]
NASA announced on 24 August 2026 that agreements signed on 14 August would let Caltech operate both missions and their science data systems for up to five years. NASA retains ownership and says both continue collecting data. The later record therefore does not support describing these two missions as shut down. [52]
The 2027 NASA request separately proposes $3.894 billion for science, compared with $7.250 billion enacted for 2026. That documents proposed funding priorities; it does not prove those cuts were enacted or that all climate monitoring was disabled. [53]
A 2023 peer reviewed study examined Exxon’s historical climate projections. It found that the company’s scientists predicted warming with substantial accuracy while company public statements contradicted important parts of its own scientific findings. This is evidence about Exxon’s historical communications, not a finding about every oil company or every statement today. [31]
An April 2024 congressional staff report, based on company records, described differences between public climate commitments and private planning or lobbying at Exxon, Chevron, BP, Shell and industry associations. It is an attributed investigative finding supported by cited documents, not a court judgment. The report also records public opposition by some companies to particular methane rollbacks, which shows why the industry should not be treated as having one position on every policy. [32]
AP reported that Trump called climate change a “con job” in his 23 September 2025 UN speech. NASA’s science explanation identifies human greenhouse gas emissions, particularly fossil fuel burning, as the driver of recent warming. The statement and the scientific evidence can be compared directly. The comparison does not establish his private reasons for making the statement. [30,54]
Clear public information helps people evaluate both climate risks and policies affecting fossil fuel businesses. Removing or obscuring it can make that evaluation harder. That is an information‑access consequence; no dollar amount of personal investment gain is assigned to the website changes.
The financial record and the policy record answer different parts of the same question. The first identifies Trump’s economic interests. The second shows what the administration did, which businesses may benefit and what environmental effects are expected. Putting them together makes the overlap visible without turning an incentive into a proven motive.
Question | What the records establish | What they do not yet establish |
|---|---|---|
How much oil and gas investment? | $11,978,142–$44,131,000 across 47 identified issuers and 178 holdings rows in the 2025 disclosure. [1,27] | An exact current total or complete indirect exposure through funds. |
Were there purchases during policy changes? | 244 identified purchases and sales in six companies share the 2025 policy calendar. [1,27] | Who instructed each trade, intraday ordering or holdings on every decision date. |
Did a connected business receive a specific approval? | DOE extended Golden Pass’s export deadline; Exxon is an owner. [36] | The amount this approval added to Exxon profit or Trump income. |
Can repeals increase climate pollution? | EPA projects additional power plant carbon dioxide under its repeal scenario. [44] | The exact future outcome or a personal profit amount tied to those emissions. |
Was climate information restricted? | Specific removals, rewrites and archiving are documented. [45,46,48,50] | A single order deleting all climate information, or a measured investment return from a website edit. |
Were NASA carbon missions terminated? | Termination efforts were reported; NASA later announced continued operations through Caltech agreements. [51,52] | A completed shutdown of OCO‑2 or OCO‑3. |
A separate Rhodium Group model projected US emissions in 2035 at 26–35% below 2005 levels, compared with 38–56% in its previous outlook. The 2025 model includes changed policy and other assumptions, including expected EPA rollbacks. This supports examining a slower decline in emissions; it is not a calculation of damage caused by one person or a forecast probability. [55]
The practical finding is a documented overlap between retained investments and policies affecting the same businesses, alongside documented changes in climate protections and public information. Exact personal gains from individual climate decisions remain unmeasured.
The four‑company total is a bounded subtotal of identified connections, not a complete inventory of every business that might benefit. It includes differing security types and relationships. A larger speculative total would conceal the missing company‑specific links. [1,27]
Company | 2025 disclosed range | Greenland connection |
|---|---|---|
Halliburton | $18,004–$97,000 | Services agreement announced; project receipts and margin not disclosed. [75] |
Lockheed Martin | $1,332,008–$5,881,000 | Tanbreez discussions reported. [79] |
RTX | $1,896,008–$6,915,000 | Tanbreez talks were planned. [79] |
Boeing | $2,132,007–$10,380,000 | Tanbreez talks were planned. [79] |
Total: $5,378,027–$23,273,000. The three defense issuers account for $5,360,023–$23,176,000. These holdings are already included in the report’s oil and defense totals and must not be added to them again. [1,27]
The European Commission identifies 25 of the EU’s 34 critical raw materials in Greenland. The GEUS assessment describes substantial geological potential but also historic estimates, limited information, remote conditions and infrastructure costs. A deposit is not yet a profitable mine. [77,78]
Resource group | Potential business use | Portfolio relevance |
|---|---|---|
Oil and gas | Exploration, drilling and production services. | Halliburton is the identified supplier; other oil holdings require a project‑specific link. [75] |
Rare earths | Magnets and specialized defense/industrial components. | The three defense issuers above; no verified purchase volumes or realized savings. [79,80] |
Copper, graphite and related battery minerals | Electrical systems, batteries and infrastructure. | Possible relevance to hardware and data‑center supply chains; no traced Greenland procurement for the report’s technology holdings. [77] |
Hafnium, tantalum, silicon and alloying metals | Electronics and specialized materials after processing and qualification. | Mineral occurrence alone does not establish semiconductor‑grade supply or a contract with a held company. [77] |
The broader technology basket remains $73.60 million–$337.05 million. It is not added to the Greenland subtotal: no company‑specific mineral supply path was verified in this scan. The same rule applies to oil majors with no verified current Greenland agreement. [1,27]
Bolton told the Guardian that Ronald Lauder proposed buying Greenland to Trump in 2018. [92]
The Washington Post reports that Tanbreez geologist Greg Barnes briefed White House officials in 2019; he did not meet Trump. [93]
Bluejay’s 19 June 2024 White Flame acquisition announcement referred to earlier ARCO work, placing the commercial project history before the September 2025 SEC announcement. [94]
These records establish earlier political interest and commercial activity. No reviewed record identifies when Trump or an adviser received the ARCO seismic material or shows that it prompted the acquisition proposal. Tanbreez concerns minerals; the ARCO material concerns the separate Jameson Land oil project.
The September 2025 SEC‑filed company announcement describes earlier ARCO surveys and reuse of that seismic work. March GL agreed to finance up to two exploration wells to earn up to 70% through an 80 Mile subsidiary. The proposed public combination provided a route to US capital markets. Halliburton entered as a commercial service provider, not as the owner of Greenland’s resources. [4,76]
In April 2026 Greenland Energy announced a broader Halliburton agreement including well and drilling services. It acknowledged no proved reserves or commercial discovery, high exploration costs and required Greenland approvals. Its August update moved the target permitting timeline to winter 2027. Prospective barrels are not proved reserves or current production. [75,28]
The Guardian’s 12 August account also reports Greenland’s objections to the regulatory timetable and equipment deployment. The company’s projected schedule is therefore not government authorization. [83]
Reported US efforts to steer Tanbreez away from Chinese buyers occurred in 2024, before Trump’s return to office. The commercial interest therefore predates his second‑term Greenland campaign. [79]
A concrete later contract is REalloys’ agreement executed on 20 May 2026 for 15% of Tanbreez’s monthly Phase 1 output. The initial 15‑year term starts with first commercial delivery; qualification conditions and some pricing components remain. It establishes a planned mine‑to‑processing route, not proof that the three defense issuers received minerals or financial savings. [80]
The stated opportunities include undeveloped deposits, access to investment capital and diversification of critical‑material supply. The EU signed its own raw‑materials partnership with Greenland in 2023. [76,78,80]
The evidence does not establish that imminent global oil depletion drove these agreements. The IEA’s 2025 outlook projected production capacity growing faster than demand through 2030. That dated forecast does not settle later market conditions, but it contradicts treating physical scarcity as the only explanation. [81]
Official resource references: GEUS’s Greenland critical‑materials review and the USGS East Greenland Rift Basins assessment are linked in the evidence register. Their geological scope is different; neither supplies a personal‑profit estimate for Trump. [77,82]
In July 2021, minister Pele Broberg stated: “The decision to halt oil exploration is also the story of a population that puts the environment first.” The government cited environmental and climate costs in stopping new licences. This records opposition to expanding oil exploration while older licence rights remained. [96,99]
Greenland stopped issuing new oil exploration licences in 2021, while preserving existing licence rights. The Jameson Land companies are pursuing drilling under older licences and must obtain separate operational approvals. [95,96]
Greenland’s position | Company proposal or action |
|---|---|
24 June 2021 decision, announced in July: stop new oil licensing and favor renewable energy. Four existing licences remained active at that time. [96] | The later Jameson Land venture relied on three existing onshore licences, covering about two million acres. [76] |
30 July 2026: the government said an earlier equipment‑landing approval had expired and renewal was still being processed. It warned the licence holder to obtain approvals before further logistics. [95] | White Flame moved stored camp equipment from Tasiilaq to Nerlerit Inaat. The government allowed it to remain there; onward movement awaited approvals. [95] |
The permitting process required more extensive review. [28] | March GL had committed to fund up to two exploration wells. On 11 August 2026, Greenland Energy announced a revised target for permits in winter 2027. That was a target, not an issued drilling permit. [28,76] |
Company | Earliest activity verified in this scan | Timing |
|---|---|---|
ExxonMobil / predecessor | Kanumas involvement dates to 1989. ExxonMobil withdrew its Greenland Sea licence application in early December 2013. [98] | Before 2025 |
Chevron | Awarded interests in the Umimmak and Nerleq offshore licences on 20 December 2013. [98] | Before 2025 |
ConocoPhillips | Awarded an interest in the Avinngaq offshore licence on 20 December 2013. [98] | Before 2025 |
Halliburton | Consulting agreement with March GL dated 11 April 2025; broader well services announced 27 April 2026. [4,75] | During 2025 |
Lockheed Martin | Tanbreez supply talks reported by 9 January 2025; the report did not date their beginning. [79] | By Jan 2025 |
RTX and Boeing | Tanbreez talks described as upcoming on 9 January 2025. [79] | Planned in 2025 |
The financial disclosure establishes Trump’s later holdings in these issuers, not his ownership at the earlier exploration dates. The historical offshore licences are separate from the current Jameson Land project; this scan does not establish a renewed project for ExxonMobil, Chevron or ConocoPhillips. [1,98]
The first formal application date for the proposed Jameson Land wells has not been verified. The dates above identify documented exploration, agreements and corporate entry; they are not all drilling‑application dates. The reviewed records also provide no government‑approved commercial production volume for this project.
If US control included authority over Greenland’s resource policy, Trump’s administration could open additional areas to drilling, subject to applicable law.
Trump’s pressure for control concerns territory whose government restricted new oil licensing to protect the environment. His policy favors expanded energy development. If US control included resource‑policy authority, that difference could translate into wider drilling access and potential benefits for companies in his disclosed portfolio. the supporting discussion and 5B connect the environmental policies, company activity and holdings. Additional personal profit and a financial motive for the threats are not established. [1,6,75,96,99]
This review documents at least seven separate occasions when Trump personally kept military coercion available, used coercive acquisition language or threatened tariffs over Greenland between 7 January 2025 and 17 January 2026. Three involved the military option, two acquisition pressure, and two tariff pressure. The first also involved economic coercion. [84,85,86,87,88,89,90]
Date | Trump’s statement or action | Type |
|---|---|---|
7 Jan 2025 | Kept military and economic coercion available to acquire Greenland. [84] | Military / economic |
4 Mar 2025 | Told Congress the US would get Greenland “one way or the other.” [85] | Acquisition pressure |
29 Mar 2025 | Told NBC he would not take military force off the table. [86] | Military option |
4 May 2025 (aired) | Again refused to exclude military force. [87] | Military option |
9 Jan 2026 | Said the US would act on Greenland whether its people liked it or not. [88] | Acquisition pressure |
16 Jan 2026 | Threatened tariffs against countries opposing Greenland acquisition. [89] | Tariff pressure |
17 Jan 2026 | Announced 10% tariffs, rising to 25%, on eight European countries unless a Greenland purchase agreement was reached. [90] | Tariff pressure |
Count: seven dated occasions, not seven military threats. Multiple remarks at the same event count once. The May date is the broadcast date. This is a verified minimum from the listed records, not a claim to have counted every interview, post or private conversation.
The White House’s 6 January 2026 military‑option statement is additional administration evidence; it is not counted as a separate personal statement by Trump. On 21 January he ruled out force and withdrew the announced tariff threat. [73,74,91]
In that speech, he added: “Or you can say no and we will remember.” [100]
At the NATO summit on 7 July 2026, Trump said Greenland “should be controlled by the United States.” [101]
These dated statements place the acquisition campaign alongside the $5.38 million–$23.27 million identified holdings range. Their repetition documents sustained pressure. It does not by itself establish which business would receive a new right, what additional profit would result, or the motive for an official decision. [1,27]
Date | Documented event | Financial meaning |
|---|---|---|
11 Apr 2025 | Halliburton consulting agreement. [4] | Private commercial connection; not a federal award. |
10 Sep 2025 | March GL earn‑in and public combination described. [76] | Commercial access under existing Greenland arrangements. |
6 Jan 2026 | White House kept military option open. [73] | Coercive option stated; no measured portfolio gain. |
21 Jan 2026 | Trump ruled out force in Davos address. [74] | Material subsequent statement; acquisition still sought. |
27 Apr 2026 | Broader Halliburton services announced. [75] | Potential supplier revenue; fee and profit not quantified. |
20 May 2026 | REalloys definitive offtake executed. [80] | Conditional future supply, not completed delivery. |
11 Aug 2026 | Winter 2027 permit target announced. [28] | Delay limits claims of imminent operating earnings. |
The disclosed securities provide an economic connection. For shares, company earnings may support dividends or market value; neither rises automatically with one project. For bonds, the effect follows credit quality and contractual payments. Exact holdings at each event, project receipts, costs and account‑level returns are needed to calculate a personal result. [1,27]
No defensible dollar estimate of incremental profit from US control of Greenland can be calculated from these records. There is no specified takeover scenario, resulting licence change, funded production plan, issuer cash‑flow forecast or verified personal portfolio at the relevant future date. A holding’s whole value is not its potential policy gain.
The evidence connects retained financial interests with an actual service relationship and reported mineral‑supply discussions. It also documents an acquisition campaign and changing statements about force. The available records do not establish that the policy was chosen to enrich Trump or that it has produced a quantified personal gain. [1,4,73,74,75,79,80]
Trump disclosed ownership stakes in companies that own or operate data centers, including Digital Realty and Equinix, while his administration advanced policies supporting data-center expansion. His disclosure also reports dividend income from both companies. [DC1][DC2]
Digital Realty rents data-center capacity and describes its platform as the world’s largest. Equinix provides facilities and connections for customer computing equipment. These are investments in the businesses operating the infrastructure—not simply a general interest in technology. [DC27][DC28]
The saved schedule lists Digital Realty holdings of $368,006–$845,000 across six entries. Two entries report 2025 dividends totaling $2,702–$6,000: $2,501–$5,000 on printed page 75, row 284, and $201–$1,000 on page 110, row 1282. Equinix holdings total $132,005–$381,000 across six entries; page 70, row 67 separately reports dividends of $1,001–$2,500. These are disclosed income bands, not estimates of policy-caused gains. [DC1]
On July 23, 2025, Trump signed Executive Order 14318. It directs expedited federal reviews, expanded use of environmental-review exclusions, access to suitable federal land and an initiative for financial support of qualifying data-center and component projects. Potential support includes loans, guarantees, grants, tax incentives and offtake agreements, subject to law and appropriations. The covered industries include computing chips, networking, storage and energy infrastructure. [DC2]
The order creates development and financing advantages for qualifying projects in industries represented in Trump’s portfolio. This review has not identified a Digital Realty or Equinix project-specific award under that order. A separate, documented company benefit is DOE’s November 2025 closing of a $1 billion loan to Constellation Energy Generation for the Crane nuclear restart. Constellation’s September 2024 agreement with Microsoft committed to a 20-year power purchase supporting that restart. Trump’s saved schedule includes holdings in both Constellation and Microsoft. [DC4][DC24]
A Pew Research Center survey of 10,548 U.S. adults, conducted July 20–August 9, 2026, found 60% would be not too or not at all comfortable with a new data center operating in their area. Fifty-four percent viewed data centers as mostly bad for the environment and 50% as mostly bad for home energy costs. Views about jobs and tax revenue were mixed. These findings document widespread concern without treating every American as opposed. [DC3]
In Prince William County, Virginia, residents organized and pursued litigation against the Digital Gateway development. QTS withdrew its planned project in July 2026 after years of planning and regulatory review, according to reporting quoting its withdrawal statement. Blackstone’s funds acquired QTS; Trump’s disclosed Blackstone shares connect his portfolio to the investment manager. This is a separate connection from his Digital Realty shares. [DC5][DC6][DC23]
Digital Realty and Equinix operate data-center facilities as a core business. CoreWeave operates an AI cloud across data centers. Microsoft, Amazon, Alphabet through Google, Meta and Oracle also operate data centers as part of their broader businesses. Trump’s disclosed investments in these companies connect his financial interests directly to businesses operating this infrastructure.
Blackstone is a separate investment-management connection: its funds acquired QTS, a dedicated data-center developer and operator. The disclosed holding is Blackstone stock. Nvidia, AMD, Broadcom, Micron and Cisco supply computing or networking technology; Eaton and Vertiv supply electrical or cooling infrastructure; energy companies supply power or power equipment. Their roles and company sources are identified in the table below.
Historical stock-only disclosure bands, principally December 31, 2025. Company activities are broader than any one project; the entire holding value is not attributed to data centers.
| Company | Disclosed range | Business and data-center connection |
|---|---|---|
| Alphabet Inc. | $15,900,016–$71,000,000 | Google builds and operates data centers for its cloud and other services. [DC7] |
| Apple Inc. | $14,000,009–$64,000,000 | Makes devices and software; also operates data centers and develops servers for Private Cloud Compute. [DC8] |
| Nvidia | $12,500,007–$58,001,000 | Supplies GPUs, CPUs, networking and computing systems used in AI data centers. [DC9] |
| Broadcom Inc. | $9,950,011–$44,000,000 | Supplies custom AI accelerators and networking and connectivity technology. [DC10] |
| Microsoft Corporation | $9,100,008–$42,251,000 | Operates cloud data centers supporting Azure and other services. [DC11] |
| Amazon.com, Inc. | $8,700,008–$41,500,000 | Operates Amazon Web Services cloud infrastructure and data centers. [DC12] |
| Meta Platforms, Inc. | $7,500,009–$33,100,000 | Builds and operates data centers supporting its social platforms and AI. [DC13] |
| Cisco Systems | $2,695,011–$11,600,000 | Supplies data-center networking, computing and infrastructure management products. [DC14] |
| Chevron | $2,595,010–$11,350,000 | Produces oil and gas and develops power projects for data centers; announced a Microsoft power agreement in June 2026. [DC15] |
| Micron Technology | $1,780,007–$6,700,000 | Makes memory and storage products used in data-center servers. [DC16] |
| Palantir Technologies Inc. | $1,780,007–$6,700,000 | Provides software for data integration, analysis and AI deployment. [DC17] |
| Advanced Micro Devices | $1,745,007–$6,650,000 | Supplies server processors and AI accelerators for data centers. [DC18] |
| Lam Research | $1,545,008–$6,250,000 | Makes equipment used to manufacture semiconductor chips. [DC19] |
| Oracle | $1,430,006–$5,950,000 | Runs cloud infrastructure and offers public, dedicated and other cloud deployments. [DC20] |
| NextEra Energy | $1,382,009–$2,830,000 | Electricity business; announced a partnership with Google to develop data-center campuses and accompanying generation. [DC21] |
| Applied Materials | $1,382,008–$5,830,000 | Supplies materials-engineering equipment used in semiconductor manufacturing. [DC22] |
| Blackstone Inc. | $1,332,009–$2,880,000 | An investment manager whose funds acquired QTS, a data-center developer and operator. Blackstone shares provide exposure to the investment manager; QTS is a separate portfolio business. [DC23] |
| Constellation Energy Corporation | $667,006–$1,430,000 | Generates electricity; its Microsoft power agreement supports the Crane nuclear restart, which received a federal loan. [DC24] |
| GE Vernova Inc. | $602,004–$1,280,000 | Supplies gas turbines and electrical infrastructure for power generation, including data-center applications. [DC25] |
| Eaton Corporation plc | $567,005–$1,181,000 | Supplies electrical distribution, backup power and power-management systems for data centers. [DC26] |
| Digital Realty Trust | $368,006–$845,000 | Owns and operates data-center infrastructure and rents capacity to customers. Its website describes its offering as the world’s largest data-center platform. [DC27] |
| Equinix | $132,005–$381,000 | Operates data centers where customers house equipment and connect to networks and cloud providers. [DC28] |
| Vertiv Holdings Company | $117,004–$330,000 | Supplies power, cooling, racks and related infrastructure for computing facilities. [DC29] |
| CoreWeave, Inc. | $1,001–$17,000 | Operates an AI cloud using specialized computing infrastructure across data centers. [DC30] |
This September 30 update starts from the existing report and its September 27 schedule of 24 company-security groups. It checks company activities against company sources, revisits key ownership and dividend entries, and reviews federal policy and public opposition. It is a light review of those named companies, not a new audit of every security in the 927-page disclosure. Holdings and transactions remain separate.
The older CoreWeave total included a separately listed $1,000,001–$5,000,000 position on printed page 7. Its instrument classification remains unresolved in this check; the stock-only schedule excludes it and reports $1,001–$17,000 from the other entries. The larger position and its reported income remain in the underlying evidence. No current holding quantity, realized policy-driven gain, or personal motive is inferred. The existing legal comparison is retained; no new legal verdict is added.
Date | Nvidia entry | Source locator |
|---|---|---|
6 May 2025 | Purchase $1,000,001–$5,000,000 | Account 6, page 323, row 224 |
12 May 2025 | Purchase $1,001–$15,000 | Account 8, page 770, row 1626 |
15 May 2025 | Purchase $15,001–$50,000 | Account 5, page 265, row 87 |
15 May 2025 | Purchase $500,001–$1,000,000 | Account 6, page 329, row 391 |
The 15 May framework and 22 May Stargate UAE announcement create a dated policy and commercial context. Nvidia and Oracle were named technology partners. The timing merits examination, but the filing does not identify who placed each trade or demonstrate use of nonpublic information. [1,10,11]
Thirteen defense and aerospace issuers total $8,251,059–$32,597,000 in 2025 disclosed holdings. The identified basket includes weapons suppliers, aerospace manufacturers and defense technology firms. Their disclosed securities create potential exposure to federal procurement decisions. Their full company value and the value of their government contracts cannot be attributed to Trump. [1,27]
Issuer | Sum of 2025 disclosed bands | Rows |
|---|---|---|
Boeing | $2,132,007–$10,380,000 | 7 |
Lockheed Martin | $1,332,008–$5,881,000 | 9 |
RTX | $1,896,008–$6,915,000 | 8 |
Northrop Grumman | $417,006–$930,000 | 6 |
General Dynamics | $382,006–$880,000 | 6 |
L3Harris | $183,007–$495,000 | 7 |
Huntington Ingalls | $31,003–$116,000 | 4 |
Leidos | $32,004–$130,000 | 4 |
Palantir | $1,780,007–$6,700,000 | 7 |
Kratos | $0–$1,000 | 1 |
AeroVironment | $0–$1,000 | 1 |
Textron | $50,001–$102,000 | 3 |
BWX Technologies | $16,002–$66,000 | 3 |
Thirteen‑company subtotal: $8,251,059–$32,597,000. [1,27]
The filing lists Boeing purchases on 29 January and 24 February 2025, two $1,001–$15,000 entries on 5 March, and a $50,001–$100,000 sale on 10 March. The Air Force announced Boeing’s selection on 21 March. This mixed activity matters: selecting only purchases would present an incomplete chronology. [1,7,27]
Reuters reported a development phase above $20 billion. That is a contract measure, not Trump’s investment or personal earnings. Boeing’s holdings subtotal also includes a $1 million–$5 million senior unsecured note. The common‑stock price chart does not measure that note’s return. [1,8]
A personal profit calculation still needs the shares held on the award date, trading instructions, and the contract amounts formally committed and actually paid. Palantir also fits an AI theme, but appears only in this defense basket to avoid duplicating it across sector sums.
Reuters reported a $15,001–$50,000 SpaceX purchase on 23 June 2026, disclosed in August. This adds a financial link to a government contractor beyond the 2025 basket. The White House said independent third‑party managers execute portfolio trades and follow recognized indexes. The disclosure supports economic exposure; it does not establish presidential trade instructions, a related contract award or personal profit. [29]
Several separate businesses sit behind the shorthand “Trump crypto.” A token’s market value, a stablecoin’s reserves, a mining company’s Bitcoin and an LLC’s proceeds measure different things. Combining them would exaggerate personal wealth or income.
Business | Financial relationship | What to measure |
|---|---|---|
World Liberty and WLFI | Family‑linked crypto business and token‑related interests | Entity ownership, token‑sale distributions, token holdings and sale restrictions. [1,13] |
USD1 and Stablecoin Holdco | Stablecoin business with a disclosed DT Marks SC interest | Reserve income, business fees and actual distributions, separately from coins in circulation. [1,15] |
$TRUMP and CIC Digital | Branded meme‑token ecosystem | Ownership and fee receipts, separately from headline token market capitalization. [1,27] |
American Bitcoin | Mining venture associated with Eric Trump and Donald Trump Jr. | Company ownership and holdings; do not attribute the sons’ interests automatically to their father. [23,24] |
Trump Media | Public‑company interest held through the revocable trust | Trump’s shares, company assets and liabilities separately. Company Bitcoin is not a personal wallet. [2,25] |
Schedule 1, line 114, reports DT Marks SC LLC’s 38.25% interest in Stablecoin Holdco and $196,875,000 in proceeds associated with new‑member capital contributions and sales of Class C units. DT Marks SC’s listed ownership is 69% DTTM Operations, 30% Trump family members and 1% DT Marks SC Member Corp. The full proceeds figure is not automatically Trump’s personal after‑tax income. [1]
Senate Banking Democratic staff describe a reported 16 January 2025 UAE‑linked $500 million acquisition of 49% of World Liberty, including at least $187 million up front to Trump‑family entities. The underlying private agreement is not established here. Whether that reported payment overlaps the $196.875 million disclosure remains unresolved. [13]
USD1 was announced as the settlement currency for MGX’s $2 billion Binance investment on 1 May. The SEC dismissed its Binance civil case on 29 May; it cited a policy decision. The GENIUS Act followed on 18 July. These are concrete dated connections for scrutiny. They do not by themselves establish a bargain exchanging government action for money. [15,16,17]
Reuters reported that Trump aides said business management had been handed to his children. That response concerns control; the separate beneficiary and ownership records remain relevant to economic benefit. [14]
After leaving his role as a senior White House adviser in 2021, Jared Kushner founded Affinity Partners. Saudi Arabia’s Public Investment Fund committed $2 billion. Senate Finance investigators reported a 1.25% annual management fee on that commitment, equivalent to $25 million a year in gross fees. Kushner is the sole owner of A Fin Management, the investment adviser behind Affinity Partners. [18,19]
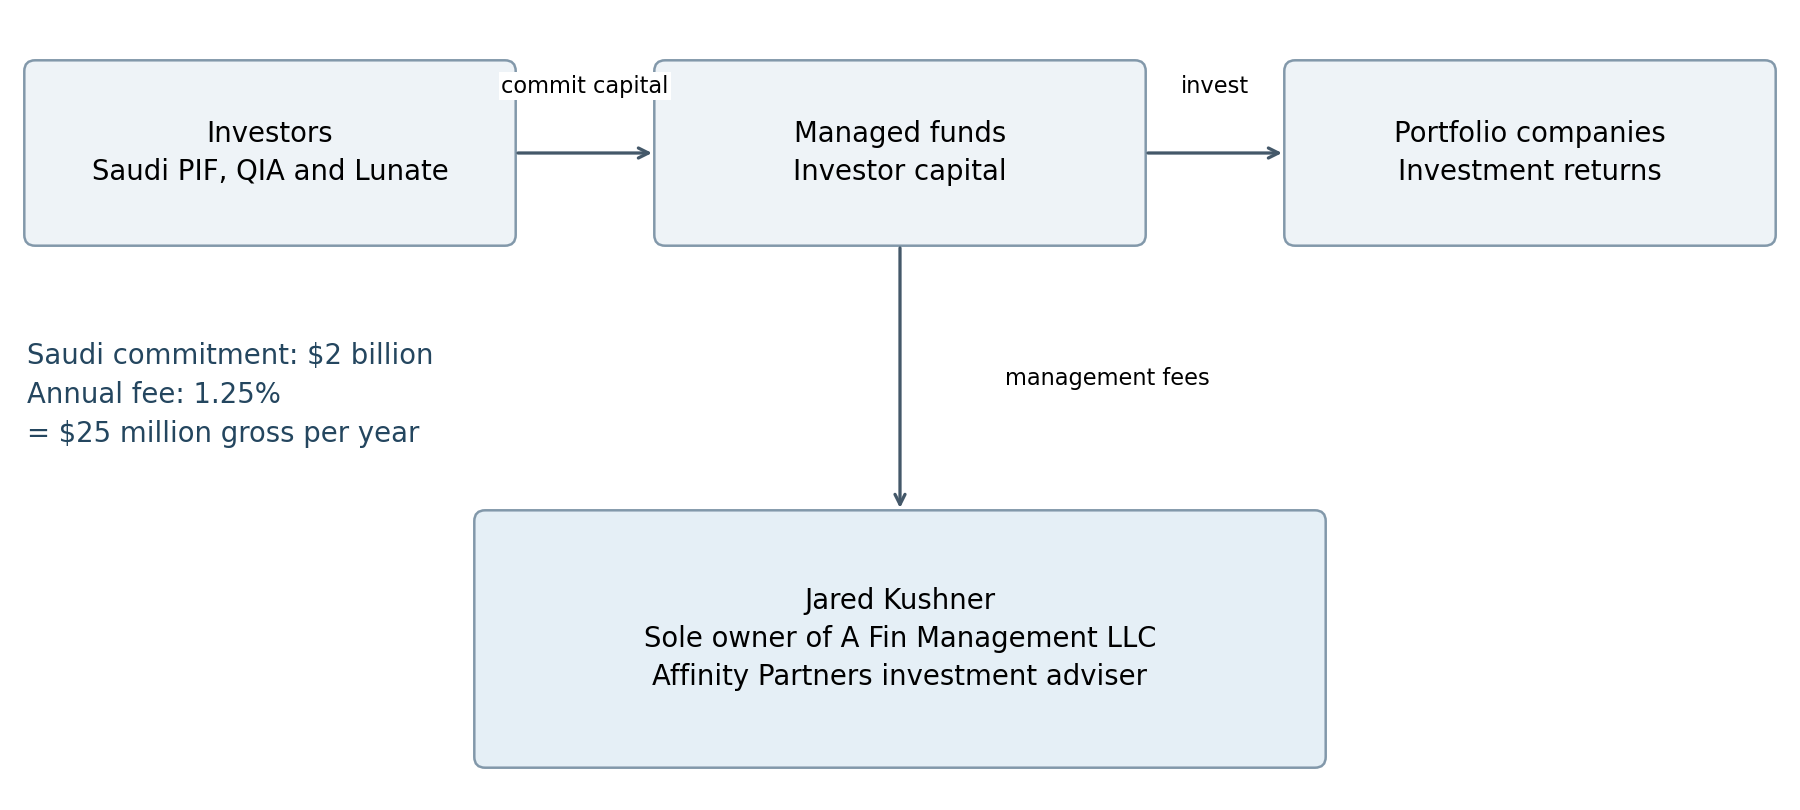
Measure | Amount and date | Financial detail |
|---|---|---|
Saudi PIF commitment | $2 billion; described in 2024 inquiry | Investor commitment, not personal wealth. [18] |
Stated annual Saudi fee | 1.25% of committed capital | At those terms, $25 million annual gross fees by arithmetic; not verified personal take‑home pay. [18] |
Foreign‑client fees | Up to $157 million by 2024 inquiry | Includes $87 million from Saudi Arabia. The $87 million is part of $157 million. [18] |
QIA and Lunate addition | $1.5 billion combined in 2024 | Separate split not stated in cited reporting. [19] |
Assets under management | $4.8 billion at end 2024; over $6 billion reported July 2026 | Managed investor assets, not Kushner’s net worth. [19,20] |
Reuters reported that Kushner was sole owner of A Fin Management LLC in the adviser filing. That ownership allows Kushner to benefit from the adviser’s profits. Money entrusted to its funds by investors is a separate pool. [19]
Date | Documented or attributed development | Why it matters |
|---|---|---|
25 Sep 2024 | Senate Finance publishes fee and foreign‑government inquiry. [18] | Dated scrutiny of economic incentives and government counterparties. |
28 Mar 2025 | Reuters reports adviser ownership and end‑2024 AUM. [19] | Defines whose business receives fees and separates capital from earnings. |
27 Jul 2026 | Affinity reports Phoenix share sale and over $6bn AUM. [20] | Reports a sale, retained ownership and capacity to return invested capital. |
5–6 Sep 2026 | White House depicts Kushner and Witkoff in meetings with Putin and Zelenskyy. [21] | Documents a current diplomatic role alongside the investment business. |
14 Sep 2026 | New Yorker publishes examination of investment interests and diplomacy. [22] | Additional reporting leads require independent verification. |
In July 2026, Affinity reported selling 25% of its Phoenix shares, retaining a 7.4% stake in the company, and being able to return the original investment to its limited partners. The announcement did not report a total return for every Affinity fund. [20]
Affinity receives recurring fees from foreign‑government‑linked investors. Kushner owns its investment adviser. White House photographs dated 5–6 September 2026 show him participating in meetings with the presidents of Russia and Ukraine. The records document his investment business and diplomatic participation during the same period. [18,19,21]
The New Yorker describes alleged Russian commercial proposals in reporting about diplomacy. A spokesman denied that US officials would profit. The alleged proposals are treated here as disputed reporting leads, not verified completed investments, contracts or personal income. [22]
The most useful records are investor subscription and fee agreements, current adviser ownership filings, portfolio beneficial‑ownership records, government approvals tied to individual projects, distributions to the adviser or family, and contemporaneous communications about official decisions.
The existing collection describes an interconnected business network: property and hospitality, licensing, branded products, media and digital assets. The useful question for every node is who owns it, who controls it, where its money comes from, and which government decision can affect it. [1,27]
Business type | Examples in the collection | Financial distinction |
|---|---|---|
Property and hospitality | Mar a Lago, golf clubs and other property entities | Asset value, debt, revenue and distributable profit are separate measures. |
International licensing | Projects and partners associated with the Trump brand | A project’s advertised construction cost is not Trump’s personal investment. The relevant interests are fees, equity and guarantees. |
Branded products | Books, digital collectibles, footwear, watches and other licences | Retail sales, royalties and the brand owner’s proceeds are different measures. |
Media and finance | Trump Media, Truth Social and related company ventures | Shareholder interests are recorded separately from total company assets. |
Family investment management | Kushner’s Affinity adviser and managed funds | Adviser ownership and fee income are separate from investor capital. |
Reuters estimated about $2.3 billion in Trump‑family gains across World Liberty, $TRUMP, ALT5 Sigma and American Bitcoin from mid‑2024 through April 2026, alongside about $2.3 billion in outside‑investor losses, including paper losses. Its calculations include inferred token sales and share valuations; the total is not verified cash profit received personally by Donald Trump. Some early traders profited. These are several ventures, not Bitcoin alone. [69,70]
The White House told Reuters that administration actions serve the American people. Eric Trump and Donald Trump Jr. did not respond to its requests for comment. [70]
Trump’s transfer of assets into a revocable trust did not end his financial interest. The cited SEC filing identifies him as the sole beneficiary and Donald Trump Jr. as sole trustee. The ownership record therefore remains relevant even when someone else manages a business or chooses investments. [2]
The 2025 disclosure shows investments in oil and gas, technology, and defense suppliers. The independently matched oil and gas basket totals $11.98 million–$44.13 million. The identified technology basket totals $73.60 million–$337.05 million, and the defense and aerospace basket totals $8.25 million–$32.60 million. These ranges describe selected disclosed holdings, including some debt; they are not exact current balances or profits. [1,27]
The climate record shows administration decisions that support fossil fuel production and remove important emissions controls. Golden Pass provides a specific example: an Exxon‑linked project received an export deadline extension while Trump’s disclosure records Exxon investments and trading. EPA’s own analysis projects higher power plant carbon dioxide emissions under its September 2026 repeal. Those are distinct, documented business and environmental effects. [1,36,43,44]
The information record shows particular climate pages and tools removed, rewritten or no longer maintained. It also shows restoration commitments, remaining public datasets and continued NASA carbon monitoring under new operating agreements. Historical evidence of misleading industry communications belongs in this account, but it does not establish that every policy or website change was directed by an investment interest. [31,32,45,46,48,49,50,52]
The wider financial record includes a private Halliburton consulting agreement, Boeing’s federal aircraft award, technology decisions involving the UAE, and Trump‑family crypto business receipts. Kushner’s adviser receives fees from investment funds while he participates in diplomacy. Fund assets, company proceeds, contract values and personal earnings remain separate measures. [4,7,10,13,18,19,20,21]
Trump’s commercial interests also include political promotion: Winning Team publishes his policy‑themed books, and Trump Media distributes content through Truth Social and Truth+. The books generate royalties for his trust‑owned company. The records do not trace those profits into political spending. Branded merchandise includes the Trump‑endorsed Bible: AP traced 2024 shipments to China. TIME documented Trump Mobile delivery delays and removal of its US‑manufacturing claim; in May 2026 its CEO said shipments would begin that week. September fulfillment was not independently verified. [1,2,57,58,60,67,68]
Together, the records identify who can benefit financially, the actions that can affect those interests, and the dates on which the two overlap. They do not yet establish the exact personal gain from each policy, who directed every trade, or whether a particular official decision was made to enrich the family. Those unanswered questions define the limits of the evidence presented here.
Article I, the supporting discussion, clause 8 includes: “from any King, Prince, or foreign State.” [62]
The full clause prohibits acceptance of specified foreign benefits by a person holding an office of profit or trust under the United States without congressional consent. The relevant financial records include foreign‑state‑linked investment and fees involving Affinity, and the reported UAE‑linked World Liberty transaction. Applying the clause requires the recipient’s official status at the time, the foreign‑state connection, the benefit received and any congressional consent. Presidential coverage and the treatment of commercial receipts have been contested; this comparison does not resolve those questions. [13,18,19,62]
Article II, the supporting discussion, clause 7 includes: “any other Emolument from the United States, or any of them.” [62]
This provision addresses presidential compensation and additional benefits from the federal government or a state during the term. The report identifies holdings in federal contractors and retained business interests. A contractor’s award is not itself a payment to the President. The relevant missing records are the government payment, the recipient entity, the benefit reaching him and the legal character of that benefit. [1,2,7,62]
The subsection addresses corrupt receipt or solicitation of value “in return for: (A) being influenced in the performance of any official act”. [63]
Its comparison requires a covered official, a thing of value, a qualifying official act and a corrupt exchange. The report documents business receipts, investments and official actions; it does not supply communications or an agreement establishing that exchange. [1,13,63]
the supporting discussion(a) addresses participation “personally and substantially” in a matter involving a known “financial interest”. [65]
For covered executive‑branch officials, the provision reaches specified personal and related financial interests, with statutory exceptions and waivers. the supporting discussion(c) excludes the President and Vice President from the supporting discussion’s officer‑and‑employee coverage. Trump’s own holdings therefore cannot be presented as a the supporting discussion violation. For another official, including Kushner in any covered appointment, the necessary records include the appointment and dates, financial interest, particular government matter, participation and any applicable waiver. [64,65]
In Trump v. United States, the Supreme Court recognized absolute criminal immunity for actions within the President’s conclusive constitutional authority, at least presumptive immunity for other official acts, and no immunity for unofficial acts. The decision also limits the use of protected official conduct as prosecution evidence. These rules concern prosecution and proof; they do not erase financial ownership or decide the legality of the transactions described here. [66]
The constitutional provisions concern the source and character of benefits. The bribery statute concerns a corrupt exchange. the supporting discussion concerns covered officials’ participation in matters affecting financial interests, with an express presidential exclusion. The present records establish financial interests and selected actions; the remaining gaps include payment tracing, official status, decision participation and exchange evidence. [62,63,64,65]
This register distinguishes the event date from later reporting or disclosure. Each item links to its evidence number. The next section preserves the transaction locators that make the principal timeline examples checkable.
Date | Event | Evidence and status |
|---|---|---|
2025‑01‑16 | Reported UAE‑linked purchase of 49% of WLF for $500 million | [13] Reported private deal |
2025‑01‑20 | Unleashing American Energy executive order | [6] Official policy |
2025‑01‑20 | Trump directs Paris withdrawal and ends international climate finance plan | [33] Signed directive |
2025‑01‑20 | Federal wind leasing and permitting pause ordered | [34] Directive; later court reversal of blanket permitting halt |
2025‑01‑30 | USDA directs removal or archiving of climate landing pages | [46] Directive documented in litigation |
2025‑03‑05 | DOE extends export deadline for Exxon‑linked Golden Pass LNG | [36] Granted extension |
2025‑03‑14 | Trump signs resolution disapproving methane charge implementing rule | [37] Enacted repeal of rule |
2025‑03‑21 | Air Force selects Boeing for F47 development | [7] Government award |
2025‑04‑08 | Trump directs challenges to state climate measures and supports coal expansion | [38] Signed directive; coal order in [39] |
2025‑04‑11 | Halliburton signs March GL consulting agreement | [4] Private contract |
2025‑05‑01 | USD1 announced for $2 billion MGX investment settlement | [15] Reported announcement |
2025‑05‑12 | USDA commits to restoring climate pages during litigation | [46] Government commitment |
2025‑05‑15 | US and UAE technology framework reported finalised | [10] Reported framework |
2025‑05‑22 | G42 announces Stargate UAE with US technology partners | [11] Company announcement |
2025‑05‑29 | SEC dismisses Binance civil lawsuit | [17] Agency action reported |
2025‑06‑25 | NOAA Climate.gov archived and no longer maintained | [48] Archive date |
2025‑07‑01 | USGCRP website removal documented by EDGI | [45] Observed removal |
2025‑07‑04 | Tax law accelerates clean vehicle and home energy credit expirations | [40] Enacted law |
2025‑07‑18 | Trump signs GENIUS Act | [16] Official policy |
2025‑09‑23 | Trump dismisses climate change in UN speech | [54] Reported speech |
2025‑11‑03 | Microsoft announces UAE chip export approval | [12] Company statement reported |
2025‑12‑08 | Judge rejects blanket federal wind permitting halt | [35] Court decision reported |
2025‑12‑09 | AP reports EPA omission of fossil fuels from climate causes page | [50] Reporting date |
2026‑01‑07 | Trump directs withdrawal from IPCC and UNFCCC among international bodies | [41] Signed directive |
2026‑01‑22 | Trump says Greenland agreement remains under negotiation | [26] Reported policy statement |
2026‑02‑12 | EPA announces final rescission of vehicle climate finding and standards | [42] Final rule announced |
2026‑02‑13 | Senators seek CFIUS review of reported UAE stake in WLF | [14] Inquiry |
2026‑02‑25 | USDA climate website litigation dismissed | [47] Dismissal recorded |
2026‑06‑23 | Trump account purchases $15,001–$50,000 SpaceX shares, according to Reuters | [29] Reported trade |
2026‑06‑29 | OGE receives Trump annual report for 2025 | [1] Disclosure received |
2026‑07‑27 | Affinity reports Phoenix sale and more than $6 billion AUM | [20] Company statement |
2026‑08‑11 | Greenland Energy targets winter 2027 permit timeline | [28] Company target |
2026‑08‑14 | NASA and Caltech sign agreements to continue OCO‑2 and OCO‑3 | [52] Agreements; announced 24 August |
2026‑09‑05 | White House depicts Kushner and Witkoff meeting Putin | [21] Official photo caption |
2026‑09‑06 | White House depicts Kushner and Witkoff meeting Zelenskyy | [21] Official photo caption |
2026‑09‑14 | EPA signs partial power plant carbon rule repeal and proposes broader rescission | [43] Final action and separate proposal |
The Halliburton table preserves all 13 identified trades. The following Boeing and Nvidia examples anchor the main policy comparisons. They are selected entries, not a complete transaction ledger. The aligned chart includes all 123 extracted entries: 13 Halliburton, 45 Boeing and 65 Nvidia. [1,27]
Date | Action | Disclosed amount | Account / page / row |
|---|---|---|---|
2025‑01‑29 | Purchase | $15,001–$50,000 | 7 / 662 / 8599 |
2025‑01‑30 | Sale | $1,001–$15,000 | 8 / 756 / 1183 |
2025‑02‑06 | Sale | $15,001–$50,000 | 7 / 699 / 9755 |
2025‑04‑04 | Purchase | $50,001–$100,000 | 7 / 604 / 6810 |
2025‑05‑05 | Sale | $50,001–$100,000 | 7 / 711 / 10102 |
2025‑05‑05 | Purchase | $1,001–$15,000 | 8 / 734 / 512 |
2025‑05‑06 | Purchase | $15,001–$50,000 | 6 / 317 / 35 |
2025‑06‑02 | Purchase | $1,001–$15,000 | 6 / 335 / 603 |
2025‑07‑01 | Sale | $15,001–$50,000 | 6 / 341 / 772 |
2025‑09‑16 | Purchase | $1,001–$15,000 | 5 / 275 / 404 |
2025‑10‑10 | Purchase | $1,001–$15,000 | 1 / 176 / 529 |
2025‑10‑29 | Purchase | $1,001–$15,000 | 1 / 181 / 699 |
2025‑12‑17 | Purchase | $1,001–$15,000 | 1 / 201 / 1313 |
Issuer and date | Action and amount | Account / page / row |
|---|---|---|
Boeing2025‑01‑29 | Purchase $15,001–$50,000 | 7 / 627 / 7513 |
Boeing2025‑02‑24 | Purchase $15,001–$50,000 | 7 / 643 / 8016 |
Boeing2025‑03‑05 | Purchase $1,001–$15,000 | 8 / 742 / 775 |
Boeing2025‑03‑05 | Purchase $1,001–$15,000 | 8 / 788 / 2190 |
Boeing2025‑03‑10 | Sale $50,001–$100,000 | 7 / 708 / 10032 |
Nvidia2025‑05‑06 | Purchase $1,000,001–$5,000,000 | 6 / 323 / 224 |
Nvidia2025‑05‑12 | Purchase $1,001–$15,000 | 8 / 770 / 1626 |
Nvidia2025‑05‑15 | Purchase $15,001–$50,000 | 5 / 265 / 87 |
Nvidia2025‑05‑15 | Purchase $500,001–$1,000,000 | 6 / 329 / 391 |
Issuer aliases were matched to the saved 6,134‑row holdings extraction and each unique account/page/row retained once. Lower bounds and upper bounds were summed separately. “None or less than $1,001” was treated as $0–$1,000. Separate accounts and distinct disclosure rows were not merged merely because their descriptions matched. Family‑trust schedules and fund look‑through exposure are not added to the named‑company basket.
Adding the reported ranges gives a lower and upper bound. It does not give a best estimate, a statistical confidence interval or the exact amount spent. Purchases and sales are gross flows across a year and cannot be substituted for a balance. Security descriptions must be retained because stock, bonds and fund interests behave differently.
The six‑company oil timeline includes 244 transactions checked against the original PDF by account, page and row. It excludes seven Sherwin‑Williams entries that had been grouped with Williams Companies in the saved data. The 54‑company oil screening list yielded 47 issuers with matching holdings; seven had no matched rows and are not assigned a value. The total remains $11,978,142–$44,131,000. [1,27]
The price dataset supplies 250 daily observations per instrument for 2025. The shared chart rebases adjusted closes to 100 on 2 January. Event‑day return is adjusted close on the event date divided by the prior trading day’s adjusted close, minus one. The later comparison uses the twentieth trading session after the event. No return is assigned to the president personally.
The full 47‑issuer basket is shown below so the $11,978,142–$44,131,000 range can be checked without relying on a six‑company sample. Each row sums distinct accounts and filing entries. Bonds and stock are retained as reported; indirect holdings through funds are not added. [1,27]
Issuer | Disclosed value range | Rows |
|---|---|---|
Chevron | $2,595,010–$11,350,000 | 10 |
Exxon Mobil | $3,180,009–$12,450,000 | 9 |
ConocoPhillips | $647,008–$1,430,000 | 8 |
Kinder Morgan | $1,169,008–$5,461,000 | 9 |
Williams | $418,007–$945,000 | 7 |
Halliburton | $18,004–$97,000 | 6 |
Occidental | $1,017,004–$5,083,000 | 7 |
SLB | $32,004–$130,000 | 4 |
EOG Resources | $101,002–$266,000 | 3 |
Phillips 66 | $383,007–$896,000 | 8 |
Marathon Petroleum | $353,006–$745,000 | 6 |
Valero | $348,008–$795,000 | 8 |
Baker Hughes | $268,007–$695,000 | 7 |
Devon Energy | $118,005–$346,000 | 6 |
Diamondback | $168,006–$446,000 | 7 |
Cheniere | $52,003–$130,000 | 3 |
Oneok | $168,006–$446,000 | 7 |
Targa | $66,003–$165,000 | 3 |
Coterra | $3,003–$47,000 | 5 |
Expand Energy | $81,004–$217,000 | 6 |
EQT | $132,005–$381,000 | 6 |
HF Sinclair | $50,001–$101,000 | 2 |
Hess | $0–$1,000 | 1 |
Liberty Energy | $100,001–$250,000 | 1 |
Oceaneering | $50,001–$100,000 | 1 |
Tidewater | $50,001–$100,000 | 1 |
Ovintiv | $50,001–$102,000 | 3 |
Chord Energy | $50,001–$102,000 | 3 |
Helmerich Payne | $50,001–$100,000 | 1 |
Archrock | $50,001–$100,000 | 1 |
DT Midstream | $51,002–$115,000 | 2 |
Magnolia Oil Gas | $50,001–$101,000 | 2 |
TechnipFMC | $16,002–$65,000 | 2 |
APA | $16,002–$67,000 | 4 |
SM Energy | $15,001–$50,000 | 1 |
Kinetik | $15,001–$50,000 | 1 |
Crescent | $15,001–$50,000 | 1 |
Talos | $15,001–$50,000 | 1 |
Northern Oil Gas | $15,001–$50,000 | 1 |
NOV | $1,001–$16,000 | 2 |
Weatherford | $1,001–$17,000 | 3 |
Core Laboratories | $1,001–$15,000 | 1 |
Patterson UTI | $0–$1,000 | 1 |
Matador | $0–$2,000 | 2 |
Murphy Oil | $0–$2,000 | 2 |
ChampionX | $0–$2,000 | 2 |
Nabors | $0–$1,000 | 1 |
Total • 47 issuers • 178 entries • $11,978,142–$44,131,000
The separate Senate staff basket is $12,541,161–$45,557,000. Its membership differs. The two ranges are alternatives, not amounts to combine. Neither is an exact measure of oil exploration acreage, cash invested originally, or personal profit. [3]
Use these account / printed page / row locators in evidence [1]. They preserve the precise rows behind the most important issuer totals. Other issuer rows remain in the saved financial collection under their source‑linked securities records.
$3,180,009–$12,450,000 • 9 rows
1 / 11 / 190; 2 / 19 / 69; 3 / 26 / 178; 4 / 37 / 239; 6 / 77 / 379; 7 / 101 / 905; 7 / 103 / 975; 8 / 136 / 894; 8 / 136 / 895
$2,595,010–$11,350,000 • 10 rows
1 / 10 / 125; 2 / 18 / 37; 3 / 24 / 118; 4 / 36 / 198; 4 / 36 / 199; 6 / 77 / 378; 7 / 91 / 474; 7 / 113 / 1373; 8 / 136 / 883; 8 / 136 / 888
$647,008–$1,430,000 • 8 rows
2 / 18 / 47; 3 / 24 / 132; 4 / 32 / 57; 6 / 75 / 277; 7 / 92 / 537; 7 / 108 / 1166; 8 / 133 / 772; 8 / 134 / 796
$1,169,008–$5,461,000 • 9 rows
1 / 13 / 252; 2 / 19 / 95; 3 / 27 / 230; 5 / 57 / 457; 6 / 75 / 272; 7 / 104 / 1018; 7 / 111 / 1313; 8 / 129 / 584; 8 / 134 / 795
$418,007–$945,000 • 7 rows
3 / 31 / 381; 5 / 59 / 531; 5 / 63 / 701; 6 / 76 / 338; 7 / 109 / 1244; 8 / 133 / 740; 8 / 133 / 761
$18,004–$97,000 • 6 rows
1 / 12 / 216; 4 / 45 / 582; 6 / 69 / 22; 7 / 81 / 64; 8 / 128 / 565; 8 / 146 / 1273
$15,900,016–$71,000,000 • 16 rows
1 / 8 / 72; 1 / 8 / 73; 2 / 17 / 8; 2 / 17 / 9; 3 / 23 / 66; 4 / 31 / 4; 4 / 38 / 293; 4 / 38 / 294; 6 / 77 / 348; 6 / 77 / 360; 7 / 91 / 480; 7 / 96 / 696; 8 / 134 / 813; 8 / 135 / 827; 8 / 135 / 841; 8 / 135 / 846
$12,500,007–$58,001,000 • 8 rows
1 / 14 / 305; 2 / 20 / 115; 3 / 28 / 277; 5 / 65 / 786; 6 / 74 / 255; 7 / 104 / 1025; 8 / 128 / 548; 8 / 128 / 563
$1,001,002–$5,017,000 • 4 rows
1 / 7 / 2; 7 / 104 / 1004; 8 / 142 / 1132; 8 / 142 / 1133
$2,132,007–$10,380,000 • 7 rows
1 / 7 / 19; 2 / 18 / 28; 3 / 24 / 103; 7 / 80 / 46; 7 / 114 / 1416; 8 / 140 / 1023; 8 / 140 / 1024
$1,332,008–$5,881,000 • 9 rows
1 / 13 / 265; 3 / 27 / 242; 5 / 52 / 253; 5 / 57 / 465; 6 / 70 / 73; 7 / 99 / 831; 7 / 104 / 1007; 8 / 133 / 769; 8 / 134 / 788
$1,896,008–$6,915,000 • 8 rows
1 / 15 / 351; 2 / 20 / 130; 3 / 29 / 318; 6 / 76 / 337; 7 / 94 / 601; 7 / 103 / 986; 8 / 134 / 807; 8 / 134 / 808
Trust and Trump Media transfer: Part 3, printed page 4. Mar a Lago: Schedule 1, line 180. DT Marks SC: Schedule 1, line 114 and cross‑reference to line 204. Boeing senior unsecured note: Part 6, account 1, printed page 7, row 19. Halliburton disclosed dividend: Part 6, account 1, page 12, row 216. [1]
In the Trump money collection, look for the trust, Halliburton securities, Alphabet securities, Nvidia securities, World Liberty, and Affinity or Jared Kushner records. The same entity can have multiple mapped locations. A geographic marker identifies where an entity or event is recorded; it does not establish that all of its assets or activities occur at that coordinate. [27]
Bracketed numbers in the report refer to these records. Source descriptions distinguish filings, official announcements, company statements, congressional staff analysis and journalism. Links open the underlying record; citations are not judicial authentication.
[1] Donald Trump annual financial disclosure for reporting year 2025
OGE Form 278e, received 29 June 2026. Government filing hosted by CREW, an advocacy organization. Parts 3, 6 and 7; Schedule 1. Printed page numbers are used below. The PDF has 927 pages including schedules.
[2] Trump revocable trust Schedule 13D
SEC filing, December 2025, Items 2 and 5. Establishes settlor, sole beneficiary, sole trustee and dated TMTG share count.
[3] Joint Economic Committee minority oil holdings analysis
Democratic staff analysis, August 2026, holdings table. Its oil basket is broader than the six‑company subtotal in this report. Its current‑value estimates are not adopted here.
[4] Halliburton and March GL consulting agreement
SEC Exhibit 10.29. Agreement dated 11 April 2025. the supporting discussion.10, 2.4 and 3 distinguish consulting, permitting and work‑order payments.
[5] Greenland Energy first quarter 2026 filing
SEC Form 10‑Q. Corporate and project structure, including March GL and Jameson Land. Project interests do not establish Trump ownership.
[6] Unleashing American Energy
Executive order, 20 January 2025. Policy text supporting domestic energy production and permitting changes. It is not a Greenland drilling permit.
[7] Air Force F47 contract award
US Air Force, 21 March 2025. Boeing selected for engineering and manufacturing development. Primary announcement; full page access was restricted on recheck.
[8] Boeing fighter award reporting
Reuters, 21 March 2025. Reported initial development value above $20 billion. Award value is not revenue already received or profit.
[9] Daily historical market prices
Yahoo Finance chart data for BA, HAL, NVDA and SPY, 2 January to 30 December 2025, retrieved 17 September 2026. Exact machine endpoints are linked below. Closing prices and adjusted closes are different series.
[10] US and UAE technology framework agreement
Reuters, 15 May 2025. Framework agreement reporting; a framework is distinct from each subsequent export licence.
[11] Stargate UAE announcement
G42, 22 May 2025. Company announcement of a planned 1 GW project within a broader 5 GW campus, with US technology partners.
[12] Microsoft UAE chip export approval
Reuters, 3 November 2025. Microsoft described export approvals and planned UAE investment. Announcement date is used in the chronology.
[13] Senate Banking minority World Liberty report
Democratic staff report, pages 2–6 and endnotes. The January 2025 $500 million / 49% deal is attributed reporting; underlying private purchase agreement is not reproduced here.
[14] Senators request review of reported UAE World Liberty stake
Reuters, 13 February 2026. Request for CFIUS review, reported transaction and administration response. An inquiry is not an adjudicated finding.
[15] USD1 chosen for MGX investment in Binance
Reuters, 1 May 2025. $2 billion investment settlement through USD1. This does not establish $2 billion income for Trump.
[16] GENIUS Act signing
White House, 18 July 2025. Stablecoin regulatory framework, including reserve and disclosure requirements.
[17] SEC dismisses Binance civil case
Reuters, 29 May 2025. Civil dismissal and stated regulatory‑policy rationale. Separate from the criminal case.
[18] Senate Finance inquiry into Affinity fees
Senate Finance chairman, 25 September 2024. Fee terms and cumulative foreign‑client fees as reported by investigators. Historical observations are dated.
[19] Affinity assets and ownership filing reporting
Reuters, 28 March 2025. A Fin Management ownership, $4.8 billion end‑2024 AUM and $1.5 billion combined QIA/Lunate capital addition.
[20] Affinity Phoenix stake sale and firm assets
Affinity company release, 27 July 2026. More than $6 billion AUM; sale of 25% of its Phoenix shares, retaining 7.4% of Phoenix; statement about returning original investor capital.
[21] US envoys visit Russia and Ukraine
White House photographs and captions dated 5–6 September 2026, depicting Kushner and Witkoff in diplomatic meetings.
[22] Jared Kushner dollar diplomacy reporting
The New Yorker, published 14 September 2026. Reporting on diplomacy and investment interests, including disputed allegations. Used as a lead with the denial, not as proof of a completed transaction.
[23] American Bitcoin company description
Company description. Bitcoin mining venture associated with Eric Trump and Donald Trump Jr. Corporate assets are not attributed automatically to Donald Trump.
[24] American Bitcoin proposed public combination
Reuters, 12 May 2025. Historical announcement; not used to state a current ownership percentage.
[25] Trump Media second quarter filing
SEC Form 10‑Q, period ended 30 June 2026. Company‑level activities should be distinguished from Trump personal accounts. No unsupported personal Bitcoin balance is inferred.
[26] Greenland negotiations reporting
Reuters, 22 January 2026. Public Greenland policy context; it does not establish that Halliburton directed policy or that Trump owned the project.
[27] Explorvia saved financial records and reproducible calculations
Saved Trump collection compared with the original 2025 filing. Sector sums use unique account/page/row entries in the 6,134‑row holdings extraction. 123 directly extracted transaction rows cover Halliburton, Boeing and Nvidia; a separate 244‑row oil ledger covers six issuers and overlaps the 13 Halliburton entries. Matching rules and precise locators are in the calculation appendix.
[28] Greenland Energy permitting and project planning
SEC Exhibit 99.1, company release dated 11 August 2026. Targeted permit timeline: winter 2027. Company target, not a granted permit or production milestone.
[29] SpaceX purchase and portfolio management response
Reuters, carried by South China Morning Post, 25 August 2026. Reports a $15,001–$50,000 purchase on 23 June; filing signed 12 August and made public 22 August. Includes the White House response. Original August OGE PDF located but not independently readable in this review; transaction remains attributed reporting.
[30] NASA explanation of the causes of climate change
NASA science reference, checked 17 September 2026. Explains the role of human greenhouse gas emissions, including burning fossil fuels.
[31] Assessing ExxonMobil global warming projections
Supran, Rahmstorf and Oreskes, Science, 13 January 2023, DOI 10.1126/science.abk0063. Peer reviewed analysis of company projections and public statements.
[32] Denial Disinformation and Doublespeak
House Oversight Democrats and Senate Budget Committee joint staff report, 30 April 2024. Executive summary and reproduced company documents. Congressional investigative findings, not a judicial ruling.
[33] Paris Agreement withdrawal directive
White House order, 20 January 2025, section 3. Directs withdrawal notices and ends the international climate finance plan. The order date is not automatically a treaty effective date.
[34] Federal wind leasing and permitting pause
Presidential memorandum, 20 January 2025, the supporting discussion and 2. Distinguishes offshore leasing withdrawal from the wider agency permitting pause.
[35] Court rejects blanket wind permitting halt
Reuters, 8 December 2025. Reports the court decision against the agency permitting halt. Do not describe the original blanket pause as unchanged current law.
[36] DOE extends Golden Pass LNG export deadline
Department of Energy, 5 March 2025. Identifies ExxonMobil and QatarEnergy as owners and confirms the extension. An approval is distinct from shipment revenue or shareholder profit.
[37] Methane waste emissions charge repeal
EPA status page. Congressional Review Act resolution signed 14 March 2025; implementing regulation removed from the CFR on 12 May 2025.
[38] Direction to challenge state climate policies
Executive Order 14260, 8 April 2025, section 2. Directs the attorney general to identify and challenge specified state measures; it does not itself invalidate every law.
[39] Coal production and power policy
Executive Order 14261, 8 April 2025. Coal leasing, regulatory review, exports and consideration of coal power for AI data centers.
[40] Clean energy tax credit changes
IRS explanation of Public Law 119‑21. Clean vehicle credits end for vehicles acquired after 30 September 2025; specified home energy credits end after 31 December 2025. Other energy credits remain subject to their own rules.
[41] Direction to withdraw from international bodies
Presidential memorandum, 7 January 2026. Includes the IPCC and UNFCCC among named bodies. A withdrawal direction and completed legal withdrawal are different stages.
[42] EPA repeal of vehicle greenhouse gas standards
EPA final rule announced 12 February 2026. Rescinds the 2009 endangerment finding for motor vehicles and the related greenhouse gas standards. Does not repeal every traditional air pollutant standard.
[43] EPA power plant repeal and separate proposal
EPA, 14 September 2026. Final partial repeal of 2024 carbon standards, accompanied by a broader proposed rescission. Links to both legal texts.
[44] EPA estimate of power plant repeal impacts
EPA regulatory impact analysis, September 2026. Table 3‑3, printed page 3‑14, PDF page 32; the supporting discussion and 6. Models emissions with and without the standards. Climate damage is not monetized in the cost comparison.
[45] Federal climate website changes and archive comparisons
Environmental Data and Governance Initiative, 6 August 2025. Climate chapter, printed pages 18–22, and Appendix A with before and after archive URLs. Independent monitoring of selected sites, not a census of every government page.
[46] USDA climate website litigation and restoration
Plaintiff counsel case record, Northeast Organic Farming Association of New York v. USDA, 1:25‑cv‑1529. January 2025 removal directive, May restoration commitment, later filings and dismissal on 25 February 2026. Allegations are distinguished from findings.
[47] USDA dismissal stipulation and order
Court filing dated 25 February 2026, hosted by plaintiff counsel. The case record identifies dismissal; this report does not treat it as a merits ruling that all federal climate page removals were unlawful.
[48] Archived NOAA Climate gov maps and data
NOAA archive page, checked 17 September 2026. Banner identifies the site as archived on 25 June 2025 and no longer maintained.
NOAA National Centers for Environmental Information. Public weather and climate data service, checked 17 September 2026. Remaining access is relevant to claims that all climate data disappeared.
[50] EPA removes fossil fuel explanation from climate page
Associated Press, 9 December 2025. Reports changes to the Causes of Climate Change page, including omission of human greenhouse gas emissions. Historical reported change, not a claim that every EPA page was deleted.
[51] Proposed closure of NASA carbon monitoring missions
Associated Press, August 2025. Reported administration effort to end funding for OCO‑2 and OCO‑3. Read with the later NASA operational announcement in [52].
[52] NASA and Caltech continue OCO missions
NASA, 24 August 2026. Agreements signed 14 August for up to five years; NASA retains ownership, Caltech operates missions and science data systems. NASA says both continue collecting data.
[53] NASA fiscal year 2027 budget request
NASA budget estimates, April 2026, tables BUD‑1 to BUD‑5. Distinguishes enacted 2026 funding from the 2027 request. A request is not an enacted cut or proof a satellite stopped operating.
[54] Trump climate remarks at the United Nations
Associated Press, 23 September 2025. Reports Trump describing climate change as a con job at the UN General Assembly. The scientific comparison is supplied separately by NASA [30].
[55] Taking Stock 2025 emissions projections
Rhodium Group, 10 September 2025, executive summary and methodology. Scenarios include policy through 15 July 2025 and assumed EPA rollbacks. Model results are not observed emissions or probabilities.
[56] NASA explanation of climate impacts
NASA science reference, checked 17 September 2026. Explains changes in heat, sea level, precipitation and other climate risks. Does not attribute an individual disaster to one presidential decision.
[57] Winning Team Publishing: founders and publishing mission
Publisher statement, accessed 17 September 2026. Identifies Donald Trump Jr. and Sergio Gor as co‑founders.
[58] Save America: publisher description
Publisher product page, accessed 17 September 2026. Describes Trump‑selected photographs and his political commentary.
[59] Political committee book purchase
Guardian, 22 March 2023. Reports $47,689.40 paid by the joint fundraising committee to Winning Team in May 2022; underlying FEC transaction not independently retrieved in this scan.
[60] Truth+ international launch with Newsmax
Reuters, 7 July 2025. Distribution arrangement; payment terms are not supplied.
[61] Senate inquiry into oil‑industry fundraising and policy promises
Reuters, 23 May 2024. Reports an inquiry into alleged campaign solicitation and policy promises, plus the American Petroleum Institute response.
[62] United States Constitution: official transcription
National Archives. Article I, the supporting discussion, clause 8; Article II, the supporting discussion, clause 7. Full provisions available at link.
[63] 18 USC 201: bribery of public officials
Government Publishing Office, 2024 Code edition, subsections (a) and (b)(2). Text cross‑checked against Cornell current text on 17 September 2026.
[64] 18 USC 202: presidential exception
Government Publishing Office, subsection (c). Excludes the President and Vice President from the listed conflict statutes, including the supporting discussion.
[65] 18 USC 208: financial interests in official matters
Government Publishing Office, subsections (a) and (b). Applies to covered officers and employees, subject to exclusions and exceptions.
Supreme Court, 1 July 2024. Majority opinion, pages 6–18 and 30–32: presidential criminal immunity and evidence limitations.
[67] Trump‑backed Bibles printed in China
Associated Press, 9 October 2024. Reporting based on shipping records; close to 120,000 copies shipped from China in February–March 2024.
[68] Trump Mobile delivery delays and company response
TIME, updated 13 May 2026. Documents missed delivery dates, changed US‑manufacturing language and CEO shipping assurance. This is a dated account, not confirmation of September fulfillment.
[69] Crypto gains and investor losses: methodology
Reuters, 9 June 2026. Estimates through April 2026; includes inferred token sales, share values and paper losses.
[70] Trump‑family crypto ventures and investor outcomes
Reuters, 9 June 2026. Investigation and White House response.
[71] Strategic Bitcoin Reserve executive order
White House, 6 March 2025, the supporting discussion. Forfeited Bitcoin reserve and budget‑neutral acquisition strategies; no transfer to a Trump business.
[72] SEC staff statement on meme coins
Division of Corporation Finance, 27 February 2025; updated 5 May. Staff view, not a Commission rule or binding determination about $TRUMP.
[73] White House statement on Greenland options
Reuters, 6 January 2026. Military option statement; not evidence of a completed takeover.
[74] Trump Davos address on Greenland
World Economic Forum, 21 January 2026. Host transcript states Trump ruled out force while seeking negotiations.
[75] Greenland Energy announces broader Halliburton agreement
Company announcement, 27 April 2026. Well and drilling services; exploration and permitting risks.
[76] March GL project entry and proposed public combination
SEC Exhibit 99.1, 10 September 2025. Earn‑in through 80 Mile subsidiary, legacy exploration and financing plan.
[77] Review of the critical raw material resource potential in Greenland
GEUS, MiMa 2023/1, May 2023. Mineral chapters, pages 103–105 and Table 31. Historical resources are not all compliant reserve estimates.
[78] European Commission: Greenland partnership
Official partnership description, checked 17 September 2026. Reports 25 of 34 EU critical raw materials and the 2023 raw‑materials partnership.
[79] Tanbreez acquisition and defense supply discussions
Reuters, 9 January 2025. Lockheed discussions and planned RTX/Boeing talks; not completed supply contracts.
[80] REalloys definitive Tanbreez offtake agreement
Company release, 21 May 2026. Agreement executed 20 May; 15% of Phase 1 monthly output; delivery qualifications and remaining pricing terms.
[81] Oil 2025: medium‑term supply and demand outlook
International Energy Agency, 2025 outlook. Dated forecast, not a statement of September 2026 market conditions.
[82] East Greenland Rift Basins oil and gas assessment
US Geological Survey, Professional Paper 1824‑K, published 2019, based on the 2008 assessment. Official report landing page; no recoverable quantity from it is adopted here.
[83] Greenland drilling delay and regulatory objections
Guardian, 12 August 2026. Reports Greenland regulatory objections and delay; government page was unavailable on recheck.
[84] Trump refuses to exclude force
AP, 7 January 2025. Press conference; military and economic coercion.
[85] Trump Greenland remarks to Congress
Reuters, 5 March 2025, covering the 4 March address.
[86] Trump retains military option in NBC interview
AP, 29 March 2025. Saturday interview; later coverage also appeared 30 March.
Guardian, 4 May 2025.
[88] Trump Greenland remarks at oil‑executive meeting
Reuters, 9 January 2026 event; article updated 10 January UTC.
[89] White House tariff remarks
Washington Post, 16 January 2026.
[90] Greenland‑linked tariff announcement
Reuters, 18 January 2026, reporting the previous day’s tariff announcement.
[91] Trump withdraws Greenland tariff threat
AP, 21 January 2026. Subsequent withdrawal, not counted as another threat.
Guardian, 15 January 2026. Retrospective reporting.
[93] Greenland mineral development
Washington Post, 27 July 2025. Retrospective reporting.
[94] Proposed Acquisition and Notice of General Meeting
Bluejay Mining, RNS 1550T, 19 June 2024. Company announcement.
[95] Greenland government: White Flame camp equipment and expired approval
Department of Business and Mineral Resources, 30 July 2026. Danish statement; prior approval, expiry, pending renewal and warning.
[96] Greenland stops new oil exploration licensing
AP, 16 July 2021. Decision of 24 June; existing licences preserved.
[97] Hydrocarbon potential of the Jameson Land Basin
John M Jacques, Mark Bilsland and Ruth Hoult, 14 December 2018. Company‑affiliated technical account of earlier exploration and proposed drilling targets.
[98] Greenland offshore licence awards and Kanumas history
The Arctic Institute, 20 January 2014, citing Greenland government licence announcements of 20 December 2013 and earlier Kanumas history.
[99] Greenland ministers explain environmental reasons for oil policy
SAFETY4SEA, 19 July 2021. Reports statements by Naaja H. Nathanielsen, Kalistat Lund and Pele Broberg; environmental protection and sustainable development.
[100] Trump’s Davos remarks
Guardian, 21 January 2026.
[101] Trump renews Greenland control demand at NATO summit
Le Monde, 8 July 2026, reporting remarks made on 7 July.
[102] Trump reiterates Greenland control demand
Reuters, 7 July 2026. Corroborating report of the NATO summit remarks.
Term | Meaning in this report |
|---|---|
Beneficiary | The person entitled to benefit economically from a trust under its terms. |
Trustee | The person with authority to administer trust property; that role can be separate from the beneficiary. |
Revocable trust | A trust whose governing terms permit revocation. A transfer into it does not by itself establish divestment. |
Disclosed value band | The range reported on a financial disclosure, rather than an exact market value or purchase price. |
Equity | An ownership interest. Common‑stock returns differ from the returns on a company’s debt. |
Debt security | A claim for interest and repayment under its terms, such as a bond or note. |
Market capitalization | Share price multiplied by shares outstanding at a specified time; not the same as enterprise value. |
Revenue and proceeds | Money received by a business or from a transaction. Neither automatically equals profit or personal income. |
Assets under management | Assets overseen by an investment manager. They largely belong to investors, not the manager personally. |
Management fee | Compensation paid to an adviser, often based on committed capital or assets. Gross fees are not personal net income. |
Contract ceiling | Maximum or potential contract value; distinct from funds obligated, payments made and profit earned. |
Adjusted close | Historical share‑price series adjusted for specified corporate actions or distributions; used consistently for returns. |
Potential conflict for review | A documented financial interest that may intersect with an official responsibility. It is not a finding of unlawful conduct. |
Causation | Evidence that an action produced an outcome. Timing and financial overlap can motivate inquiry without proving causation. |
Quid pro quo | An exchange of a benefit for an action. No such exchange is established merely by the timelines in this report. |
 © 2026 Explorvia Media LLC | Explorvia.com
Reviewed September 30, 2026. Company statements establish their descriptions and announcements. Public-opinion findings come from Pew; local opposition is documented separately. The earlier report’s evidence register remains below its corresponding report material.